1. The Opportunity Cost Theory of Gold Valuation
Gold possesses a unique status in the global financial architecture: it is a pure monetary asset with zero credit risk, zero counterparty risk, and infinite duration, but it pays neither a dividend nor an interest coupon.
Because physical bullion generates no cash yield, an institutional asset allocator holding gold incurs an opportunity cost equivalent to the risk-free return available on sovereign government debt after adjusting for expected inflation—specifically, the real yield on US Treasury Inflation-Protected Securities (TIPS).
The Fisher Equation expresses the relationship between nominal interest rates, real interest rates, and inflation expectations: Nominal Yield = Real Yield + Expected Inflation (Breakeven Rate) Rearranging for Real Yield: Real Yield = Nominal Yield − Expected Inflation
When real yields are high (e.g., +2.50%), holding risk-free US sovereign bonds provides an attractive real purchasing power return. In such regimes, institutional pension funds, endowments, and macro hedge funds are economically incentivized to liquidate non-yielding bullion and rotate capital into high-yielding Treasury paper.
Conversely, when real yields plunge toward zero or become deeply negative (as witnessed in 1971–1980, 2001–2011, and 2019–2020), holding paper currency or sovereign debt guarantees real purchasing power destruction. In negative real yield regimes, the opportunity cost of holding physical bullion collapses to zero, triggering massive institutional capital allocations that drive secular multi-year gold bull runs.
Real Yield (%) ≈ 10-Year Nominal Treasury Yield − 10-Year Breakeven Inflation Rate2. US 10-Year TIPS Real Yields: The Empirical Historical Baseline
Between 2003 and 2021, the econometric relationship between the Federal Reserve Bank of St. Louis 10-Year TIPS yield series (FRED: DFII10) and spot gold (XAUUSD) was one of the most reliable statistical correlations in global macroeconomics.
Linear regression models over the 2003–2021 sample period established: - Correlation Coefficient (r): Consistently between −0.78 and −0.86 on a rolling 90-day and 52-week basis. - Coefficient of Determination (R²): Exceeded 0.70, indicating that over 70% of the variance in gold prices during this period could be explained by changes in 10-Year US Real Yields alone. - Sensitivity Beta: Every 25 basis point decline in 10-Year TIPS yields historically produced an approximate $35 to $50 increase in gold valuation.
This historical relationship formed the foundation of institutional quantitative models developed by major bullion desks at Goldman Sachs, UBS, and JPMorgan: if you forecasted real yield direction accurately, you forecasted gold trend direction.
| Historical Era | 10Y TIPS Real Yield (Avg) | Gold Price Trajectory | Observed Correlation (r) |
|---|---|---|---|
| 2004–2007 (Pre-GFC) | +1.50% to +2.50% | Gradual Bull Market ($400 → $800) | −0.74 (Strong Inverse) |
| 2008–2012 (QE Expansion) | +1.50% dropping to −0.80% | Explosive Rally ($700 → $1,920) | −0.86 (Very Strong Inverse) |
| 2013–2018 (Fed Tapering) | −0.80% rising to +1.15% | Secular Bear / Consolidation ($1,900 → $1,180) | −0.81 (Strong Inverse) |
| 2019–2021 (COVID Easing) | +0.50% dropping to −1.10% | All-Time High Surge ($1,270 → $2,075) | −0.88 (Extremely Strong) |
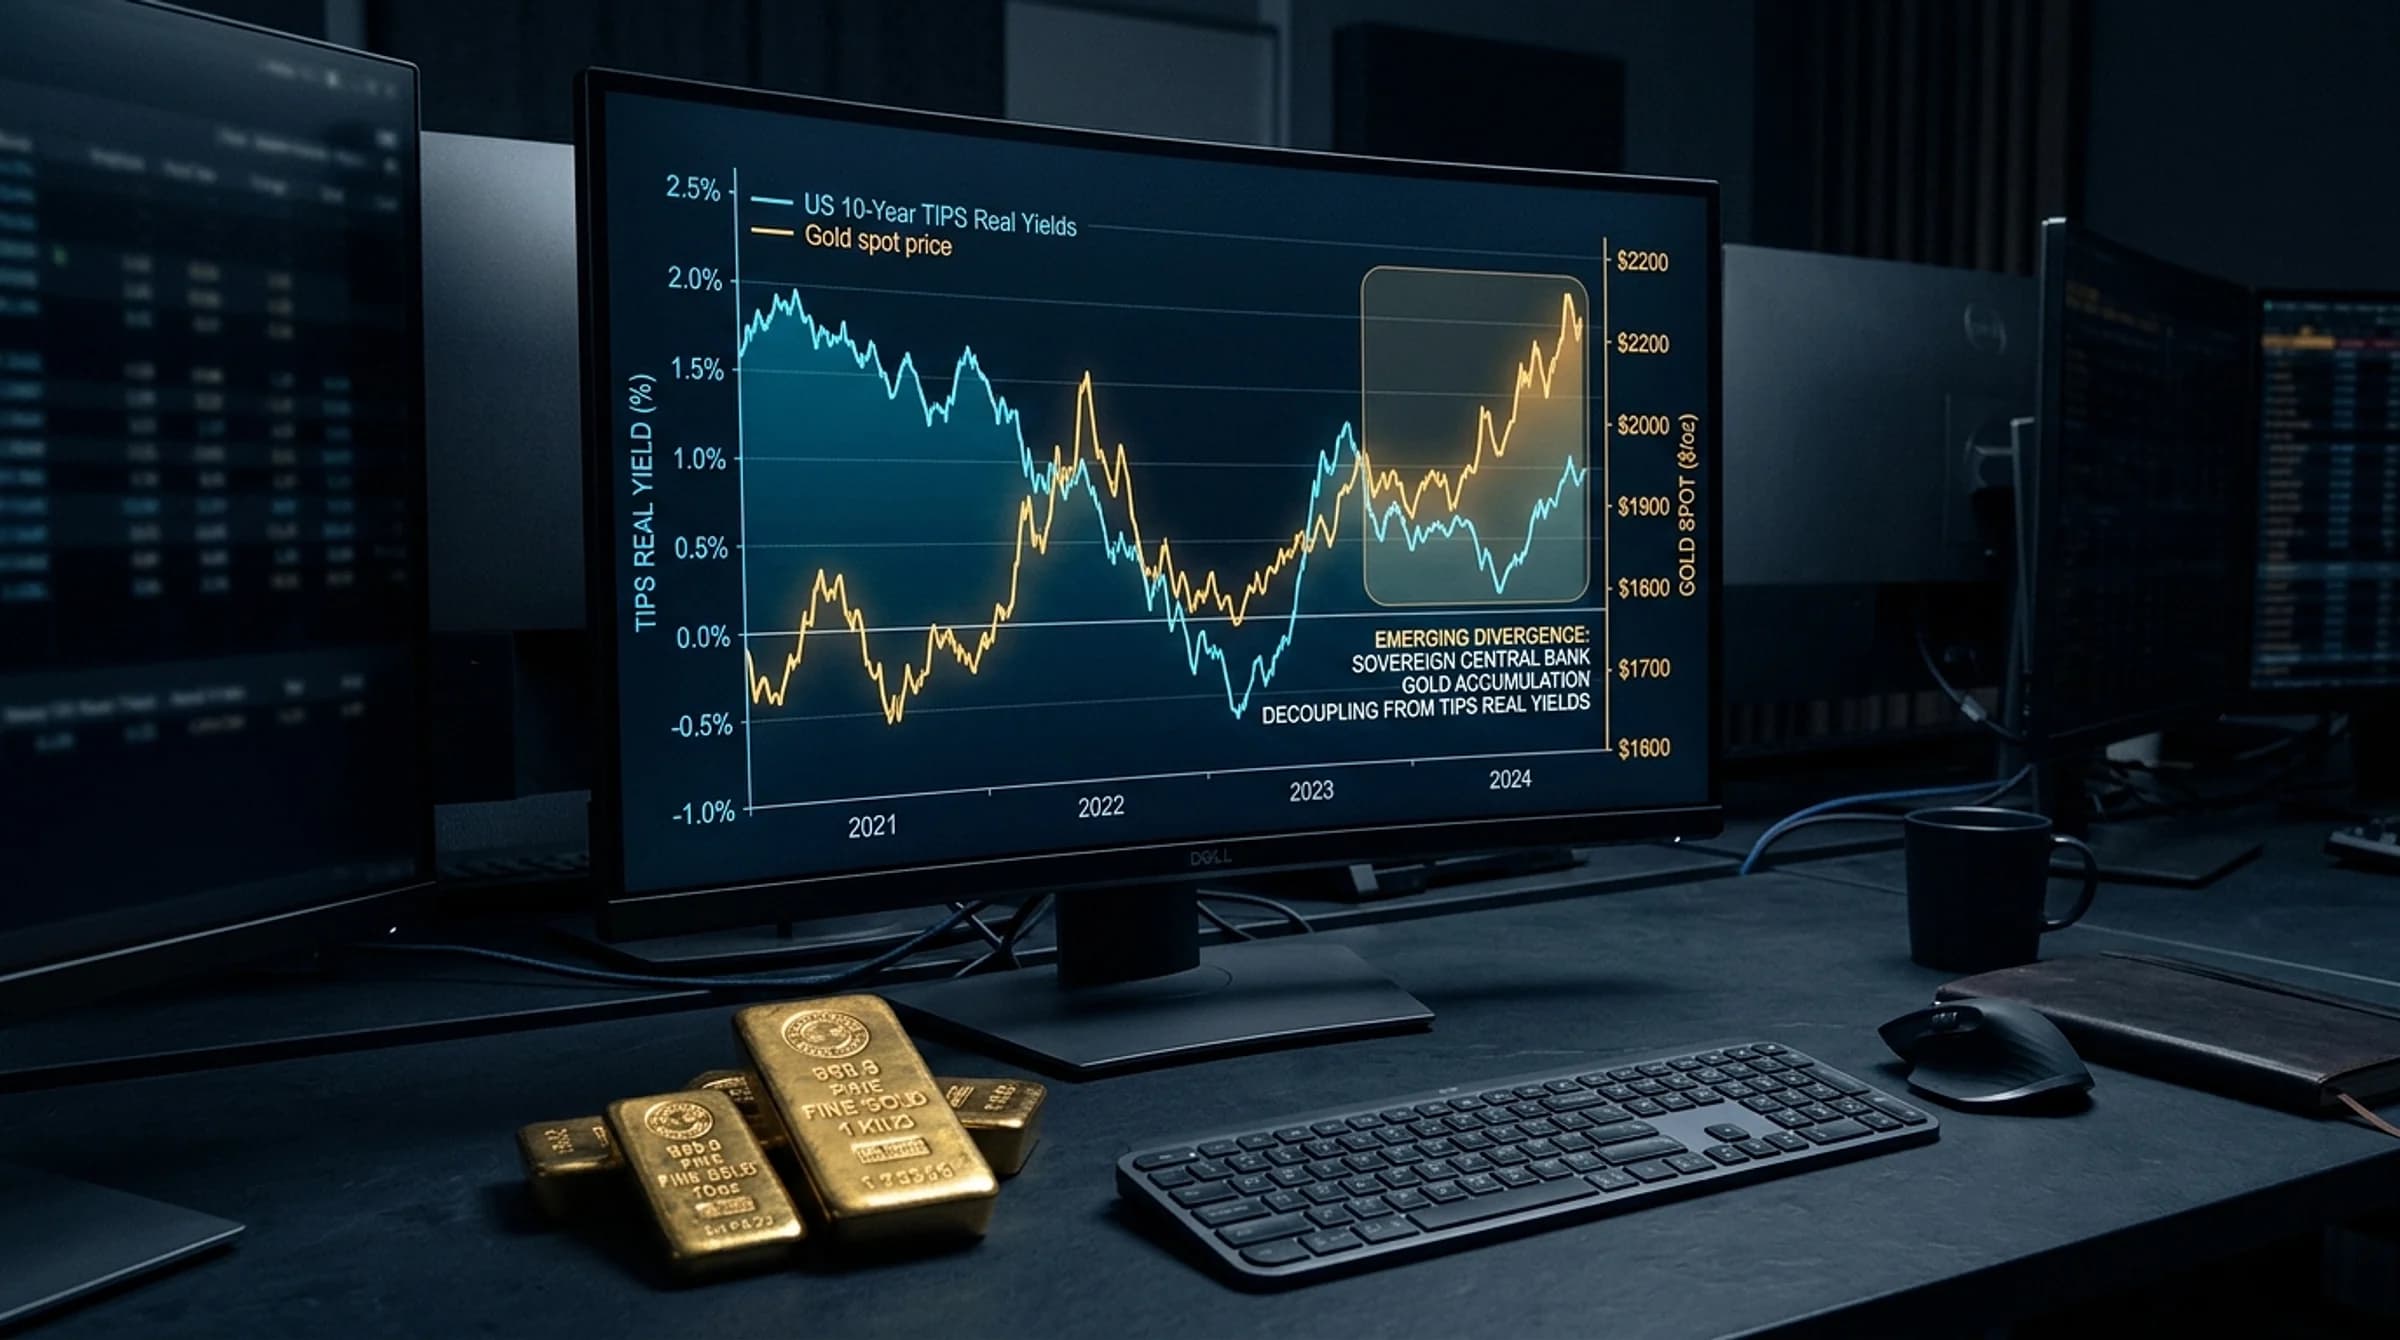
| 2022–2026 (The Decoupling) | −1.10% soaring to +2.50% | Record Highs ($1,620 → $2,700+) | +0.42 (Decoupled Regime Shift) |
3. The 2022–2026 Structural Decoupling: Why Did Gold Rally with Real Yields?
Beginning in early 2022, traditional econometric gold models broke down spectacularly. Following the Federal Reserve's aggressive interest-rate tightening cycle, US 10-Year real yields rocketed from −1.10% in late 2021 to over +2.50% by late 2023—the highest real interest rates in 15 years.
According to classical opportunity cost models, gold should have collapsed below $1,200/oz. Western gold ETFs (such as SPDR Gold Shares, ticker: GLD) behaved exactly as legacy models predicted, experiencing massive net institutional outflows of over 800 metric tons.
Yet gold did not collapse. Instead, spot gold formed a resilient triple bottom at $1,615–$1,620 in late 2022, consolidated, and then staged an explosive breakout to record all-time highs above $2,700/oz.
Why did the 20-year correlation break down? Econometric analysis identifies three structural drivers:
1. Financial Weaponization & Sovereign Sanctions: In March 2022, G7 nations froze approximately $300 billion in Russian Central Bank foreign currency reserves held in Western custodians. This action demonstrated to sovereign finance ministries worldwide that US Dollars, Euros, and Treasury bonds carry jurisdictional confiscation risk. For non-Western nations running trade surpluses, gold stored within sovereign borders became the only liquid monetary reserve asset immune to overseas legal seizure.
2. Price-Inelastic Central Bank Buying: According to World Gold Council data, global central bank gold purchases exceeded 1,000 metric tons annually in 2022, 2023, and 2024—more than double the decade average. This sovereign buying (led by the People's Bank of China, Reserve Bank of India, National Bank of Poland, and Central Bank of Turkey) was price-inelastic: central banks accumulated physical bullion continuously regardless of real yield levels or spot prices.
3. US Fiscal Dominance & Debt Trajectory: US national debt expanding past $35 trillion ($1 trillion added every 100 days) triggered growing institutional concern over long-term debt sustainability. Global capital increasingly views gold as insurance against sovereign debt debasement and eventual financial repression.
4. The US Dollar Index (DXY) Inverse Elasticity & SMT Divergence
Because spot gold is denominated in US Dollars, the foreign exchange value of the USD exerts an immediate mathematical and trade-weighted impact on gold pricing:
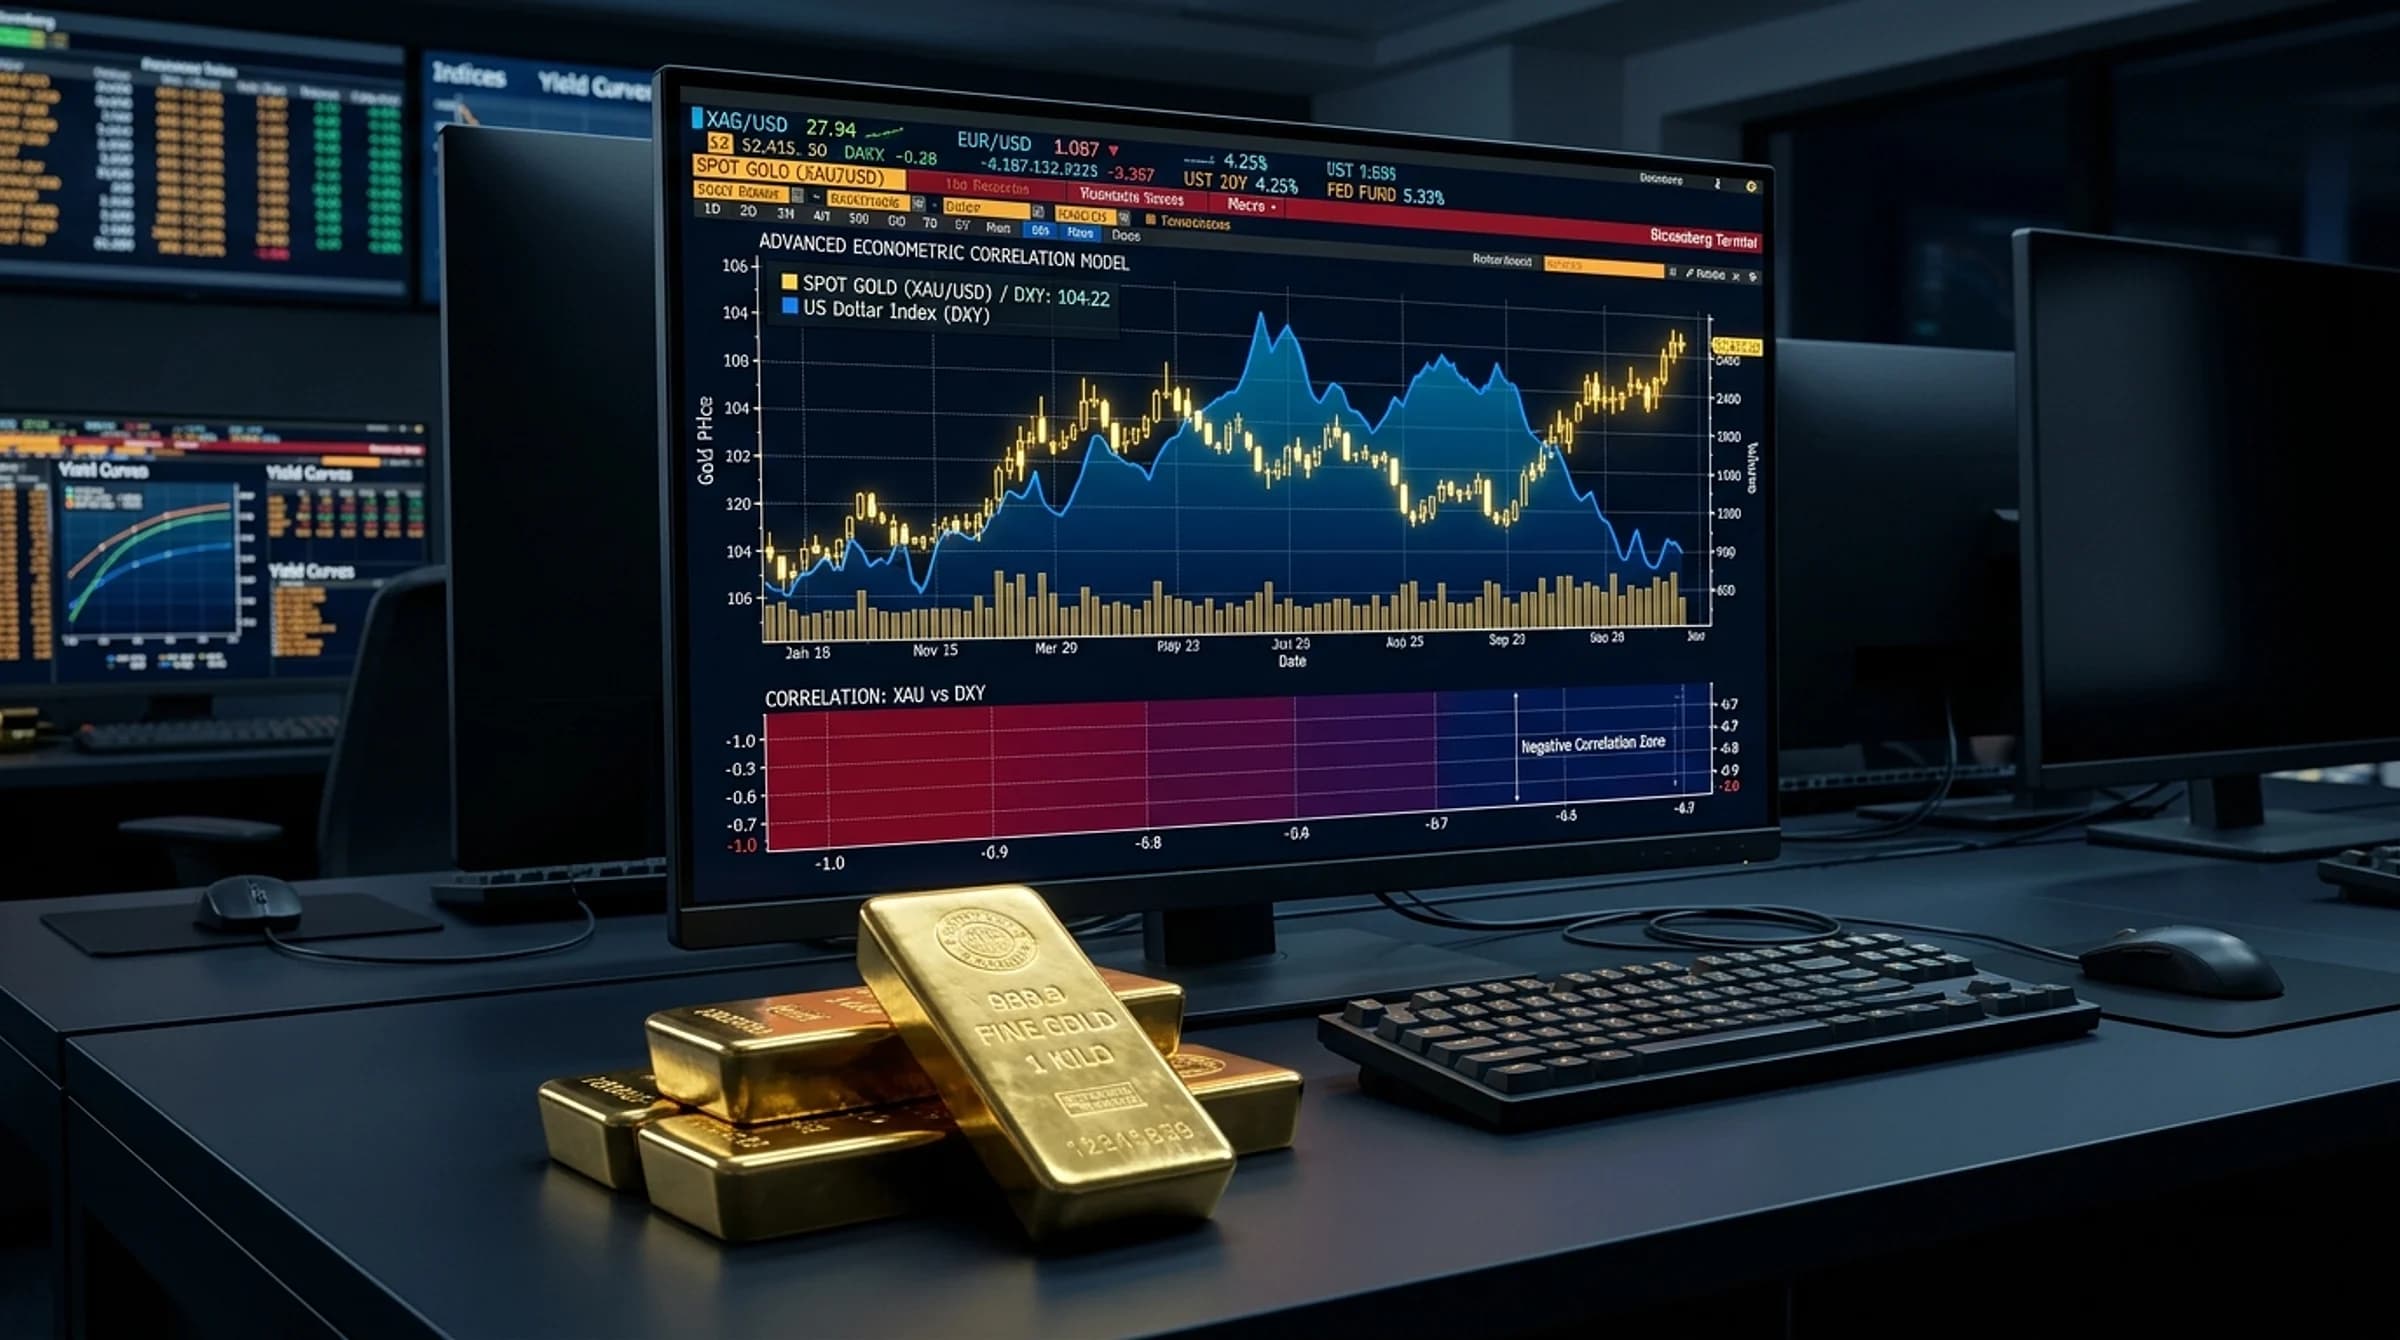
1. The Currency Denominator Effect: If the intrinsic value of gold remains completely static, but the purchasing power of the US Dollar depreciates by 10% against a global basket of currencies, it requires 10% more nominal dollars to purchase that same ounce of gold. This mechanical denominator effect generates an inverse baseline correlation between the US Dollar Index (DXY) and spot gold (historical average: r = −0.65).
2. Bilateral Purchasing Power Parity: A strengthening US Dollar renders gold significantly more expensive in local currency terms for non-USD market participants (such as Indian jewelry consumers, European wealth managers, and Chinese bullion accumulators), dampening physical retail demand.
3. The SMT (Smart Money Tool) Divergence Warning: While the baseline correlation is inverse, traders must closely watch for correlation breakdown: - Bearish SMT Divergence: DXY makes a lower low, but gold fails to make a higher high. This indicates institutional selling under the cover of dollar weakness. - Bullish SMT Divergence: DXY makes a higher high, but gold refuses to make a lower low, printing a higher low instead. This represents acute institutional accumulation, signaling that physical or sovereign demand is overwhelming dollar headwinds. - Safe-Haven Decoupling: In periods of major geopolitical escalation or banking systemic panic, capital flees regional emerging market currencies into both the US Dollar and Gold simultaneously, causing both assets to rally together.
5. Sovereign Reserves Accumulation & Physical Shanghai Arbitrage
A critical evolution in post-2022 precious metals markets is the geographic shift in price-discovery power from Western paper futures (CME Globex) to Eastern physical delivery (Shanghai Gold Exchange - SGE).
The Shanghai Physical Premium: Physical gold on the Shanghai Gold Exchange frequently trades at a substantial premium of $20 to $100 per ounce over London Loco spot quotes. This premium indicates immense domestic physical demand that exceeds the Chinese import quota allocations authorized by the People's Bank of China (PBoC).
When the Shanghai premium expands significantly: - Global bullion arbitrageurs purchase spot gold in London and Zurich and export physical metal to Asia, depleting Western vault reserves. - Comex paper short sellers face severe physical delivery risk if they attempt to suppress spot prices, because physical bullion is continuously drained from registered depository vaults. - The physical delivery drain acts as an algorithmic price floor, preventing sustained technical corrections.
| Central Bank / Entity | Annual Net Purchases (Est.) | Primary Motivation | Reserve Asset Policy |
|---|---|---|---|
| People's Bank of China (PBoC) | 200–300+ metric tons / year | De-dollarization & reserve security | Increasing gold share from 4.5% toward 10%+ |
| Reserve Bank of India (RBI) | 50–100 metric tons / year | FX reserve diversification | Repatriating offshore gold to domestic vaults |
| National Bank of Poland (NBP) | 100+ metric tons accumulated | Geopolitical buffer & balance sheet strength | Targeting 20% total reserve allocation |
| Western Retail ETFs (GLD/IAU) | Net Outflows (−300t) transitioning to neutral | Opportunity cost rotation into 5% money markets | Re-accumulates during Fed rate cutting cycles |
6. Inflation Expectations vs. Nominal Yields: The Breakeven Mechanism
Novice traders frequently assume that high headline inflation (CPI) guarantees an immediate surge in gold prices. Historically, this assumption is flawed:
If headline inflation rises to 8.0%, but the central bank hikes nominal interest rates aggressively to 10.0%, real interest rates rise (+2.0%). In this environment, gold regularly declines because the real yield on cash exceeds inflation.
Gold rallies in response to inflation only when the central bank is "behind the curve"—meaning nominal interest rates remain suppressed below the true rate of currency inflation, causing real yields to plummet.
To monitor whether macroeconomic conditions favor gold, institutional analysts track the 10-Year Breakeven Inflation Rate (FRED: T10YIE), derived from the yield spread between 10-Year nominal Treasuries and 10-Year TIPS: Breakeven Rate = Nominal 10-Year Treasury Yield − 10-Year TIPS Yield
If the 10-Year Breakeven Inflation Rate expands while nominal yields remain anchored by Fed forward guidance, gold experiences optimal fundamental tailwinds.
7. The Quantitative 4-Pillar Macro Dashboard for Traders
Institutional gold desks synthesize macroeconomic data into an objective daily 4-pillar scorecard. Traders can implement this framework to establish weekly and monthly directional bias:
| Pillar | Primary Data Indicator | Bullish Gold Regime | Bearish Gold Regime | Data Frequency |
|---|---|---|---|---|
| Pillar 1: Real Yields | FRED: DFII10 (10-Year TIPS Yield) | Falling or negative real yields (< 1.50%) | Rising real yields (> 2.00%) without sovereign bid | Daily update (16:00 ET) |
| Pillar 2: FX Denominator | US Dollar Index (DXY / Invesco UUP) | DXY downtrend or printing SMT bearish divergence | DXY aggressive upward expansion | Real-time interbank |
| Pillar 3: Monetary Policy | CME FedWatch Tool (Fed Funds Futures) | Markets pricing interest rate cuts / easing cycles | Markets pricing rate hikes or "higher for longer" | Continuous pricing |
| Pillar 4: Physical Demand | SGE Premium / Central Bank net filings | Shanghai premium > $25/oz over London spot | Shanghai at discount or parity to London spot | Daily / Monthly IMF IFS |
8. Worked Macroeconomic Scenario & Trade Thesis Formulation
Here is a practical case study demonstrating how an institutional macro analyst translates fundamental data into a trade thesis:
Data Telemetry Observed: - 10-Year TIPS Yield (DFII10): Declines over three weeks from 2.15% to 1.85% (-30 bps). - DXY Index: Tests major resistance at 104.50 and fails to make a higher high, while Gold prints a higher low at $2,630.00 (Bullish SMT Divergence). - CME FedWatch: Probability of a 50 bps Fed rate cut at the upcoming FOMC rises from 25% to 65%. - Shanghai Gold Exchange: Gold trading at a $32.00/oz premium over Loco London.
Macro Synthesis: All four pillars align in bullish harmony: 1. Real yields are compressing, reducing the opportunity cost of holding non-yielding bullion. 2. Dollar index momentum is exhausting at resistance. 3. Monetary policy expectations anticipate aggressive liquidity injection. 4. Physical demand in Asia continues absorbing Western vault inventory.
Execution Action: The research desk issues a Bullish Macro Bias to the execution team. Intraday technical setups (London Judas Swings and discount Fair Value Gaps) are prioritized exclusively for LONG execution, while short technical signals are filtered out or traded at half risk. Stop losses are anchored below weekly structural lows ($2,610.00) with a multi-week target projected toward $2,720.00.