1. The Institutional Paradigm: Demystifying ICT & SMC
In online retail trading communities, Smart Money Concepts (SMC) and the Inner Circle Trader (ICT) methodology—created by Michael J. Huddleston—are often mythologized as secret insight into central bank manipulation.
To trade gold successfully, you must strip away the mysticism and understand SMC for what it genuinely is: an elegant, rule-based price delivery model that tracks order book liquidity, market microstructure imbalances, and scheduled institutional trading windows.
Traditional retail technical analysis teaches traders to buy trendline touches, double bottoms, and breakout flag patterns. However, financial markets do not move because a line was drawn on a chart. Spot gold moves because of auction mechanics: large institutional participants (bullion clearing banks, hedge funds, sovereign desks) trade positions so massive that they cannot execute market orders without causing extreme self-inflicted slippage.
To accumulate a multi-ton long position in physical or synthetic gold, an institution requires an equal and opposite volume of willing sellers. Where do massive clusters of sell orders rest? Directly below obvious swing lows, where retail traders place their stop losses.
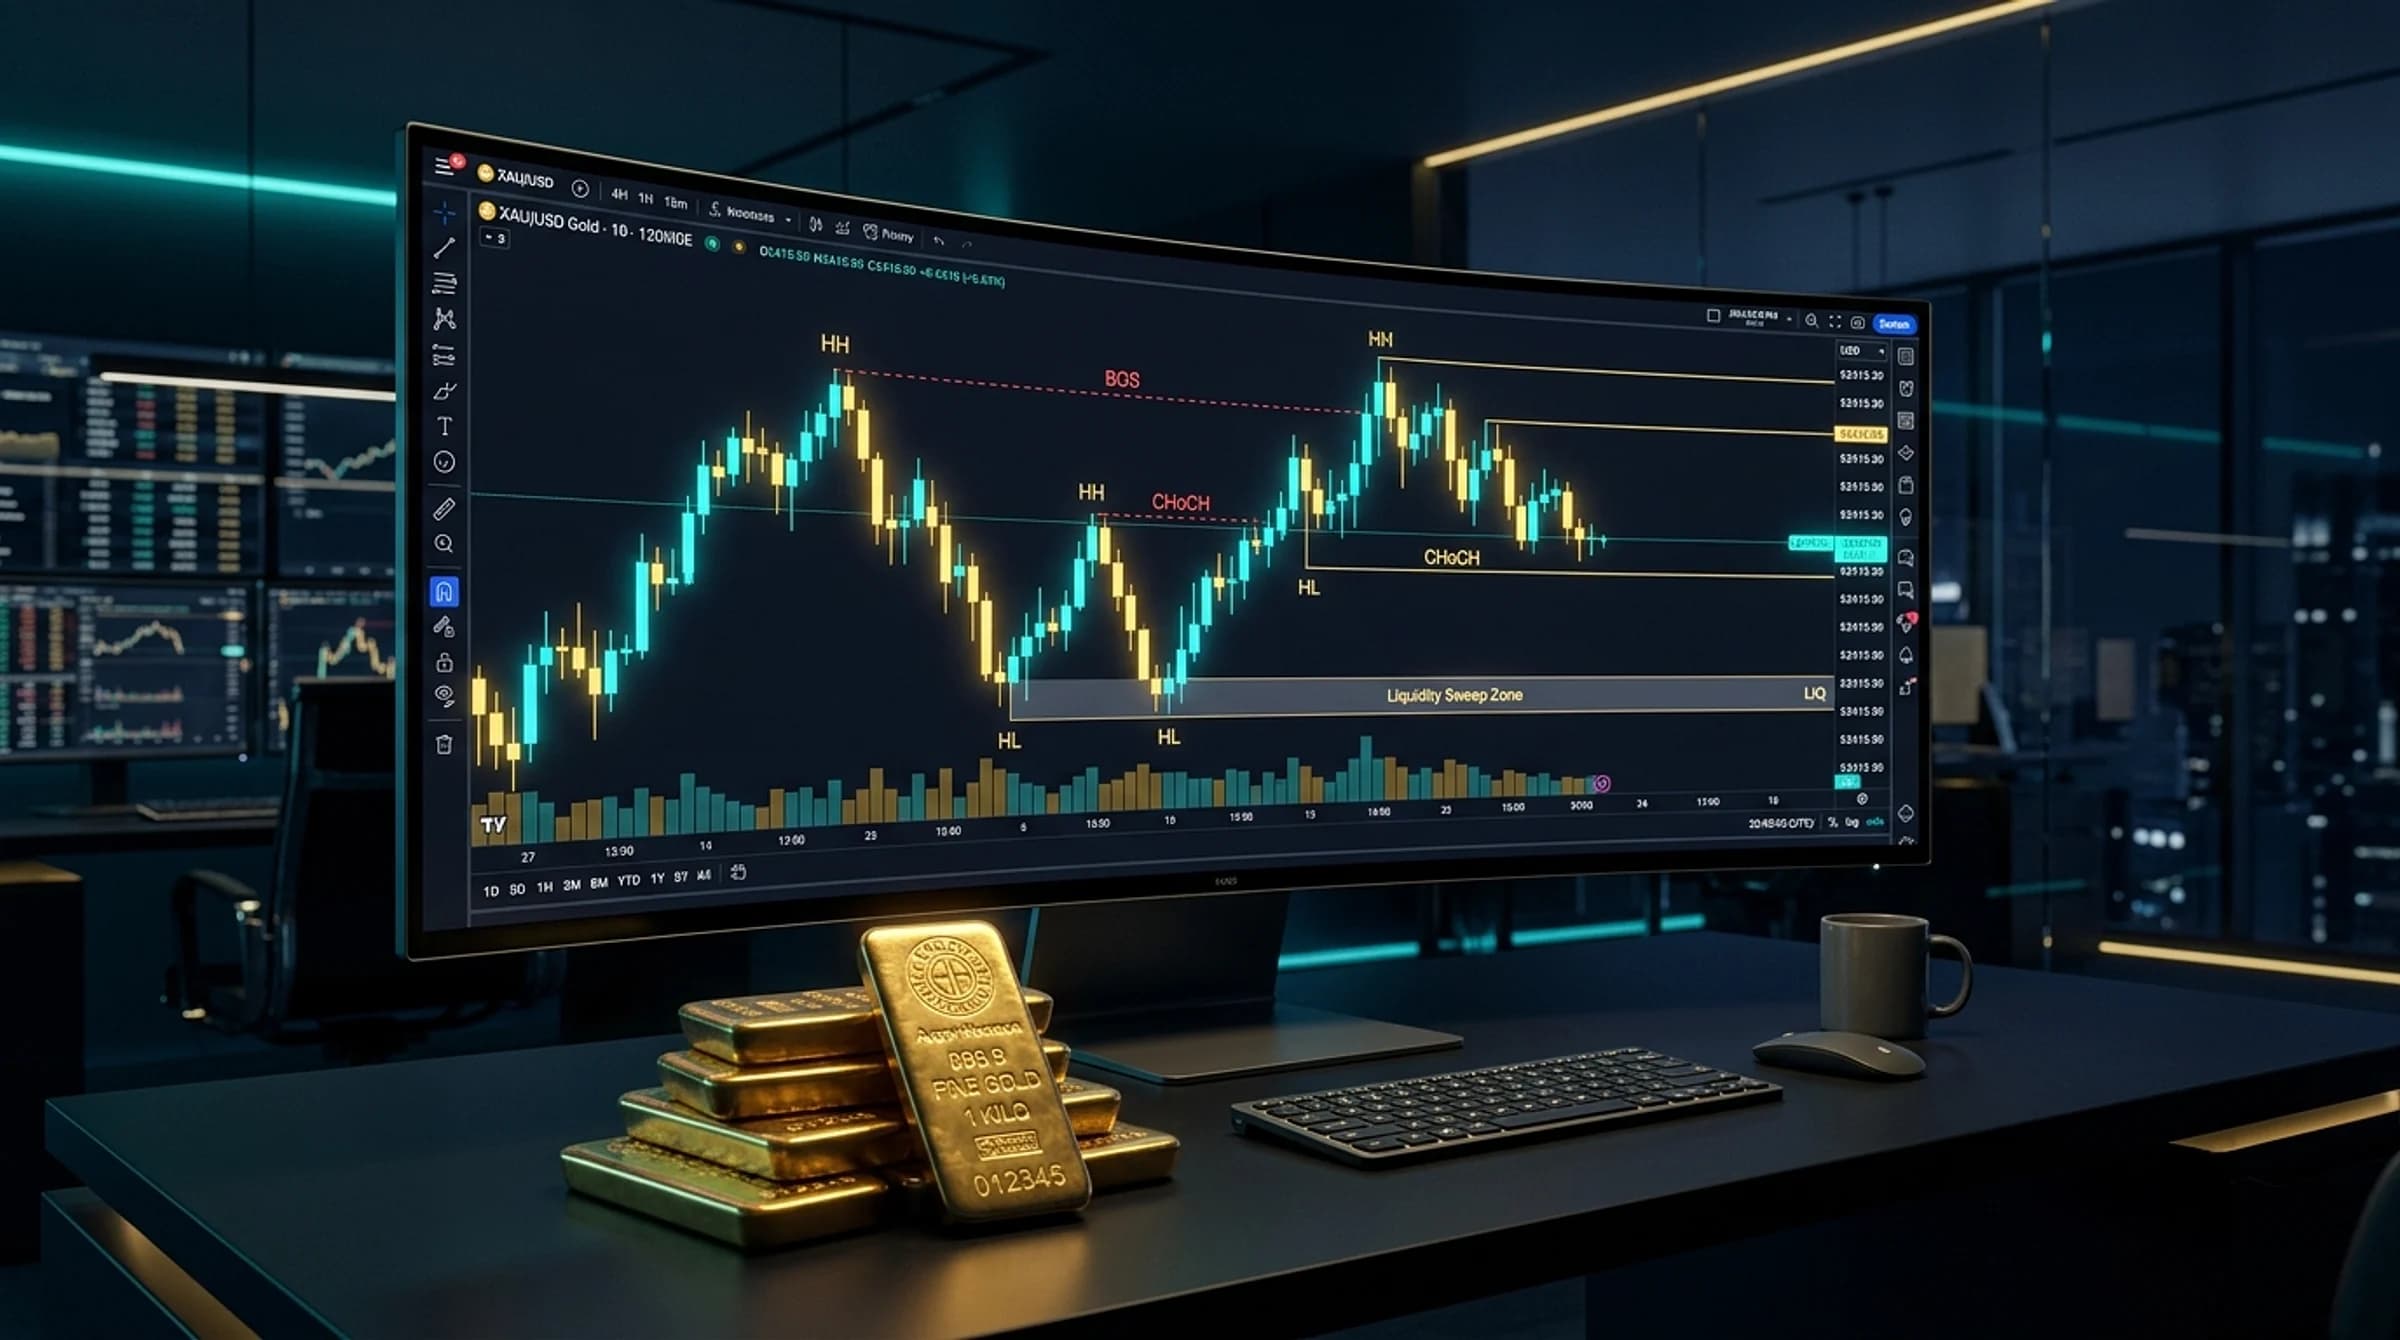
Understanding SMC means recognizing that apparent "false breakouts" and "stop hunts" are not malicious conspiracies targeted at individual retail accounts; they are the mechanical necessity of an electronic matching engine sourcing liquidity to fill institutional orders.
2. Liquidity Architecture: Buy-Side (BSL) and Sell-Side Liquidity (SSL)
Liquidity is the fuel of price delivery. Without liquidity, price cannot move. In the gold market, liquidity manifests in two primary forms:
1. Buy-Side Liquidity (BSL): BSL consists of resting buy orders clustered above prominent market highs. These orders comprise: - Buy Stop-Losses: Placed by traders holding short positions who will be forced to buy back at market if price rises. - Buy-Stop Breakout Orders: Placed by momentum breakout traders attempting to catch an upside trend expansion. When price pushes above a major swing high (e.g., the Asian session high or previous day high), these resting buy orders are triggered, creating a flood of buy liquidity. If institutions wish to enter large short positions, they sell directly into this influx of buy orders.
2. Sell-Side Liquidity (SSL): SSL consists of resting sell orders clustered below prominent swing lows: - Sell Stop-Losses: Placed by long traders protecting their capital. - Sell-Stop Breakout Orders: Placed by traders shorting downward breakdowns. When price purges a swing low, panicked long stops execute as market sell orders. Institutional accumulators utilize this concentrated liquidity pool to buy massive volume without bidding up the market.
3. External vs. Internal Range Liquidity (ERL / IRL): Market delivery perpetually cycles between External Range Liquidity (major swing highs and lows) and Internal Range Liquidity (Fair Value Gaps and Order Blocks inside the range). Once external liquidity is purged, algorithms regularly re-balance price toward internal inefficiencies before seeking the next external liquidity target.
3. Market Inefficiency: Fair Value Gaps (FVG) and Consequent Encroachment
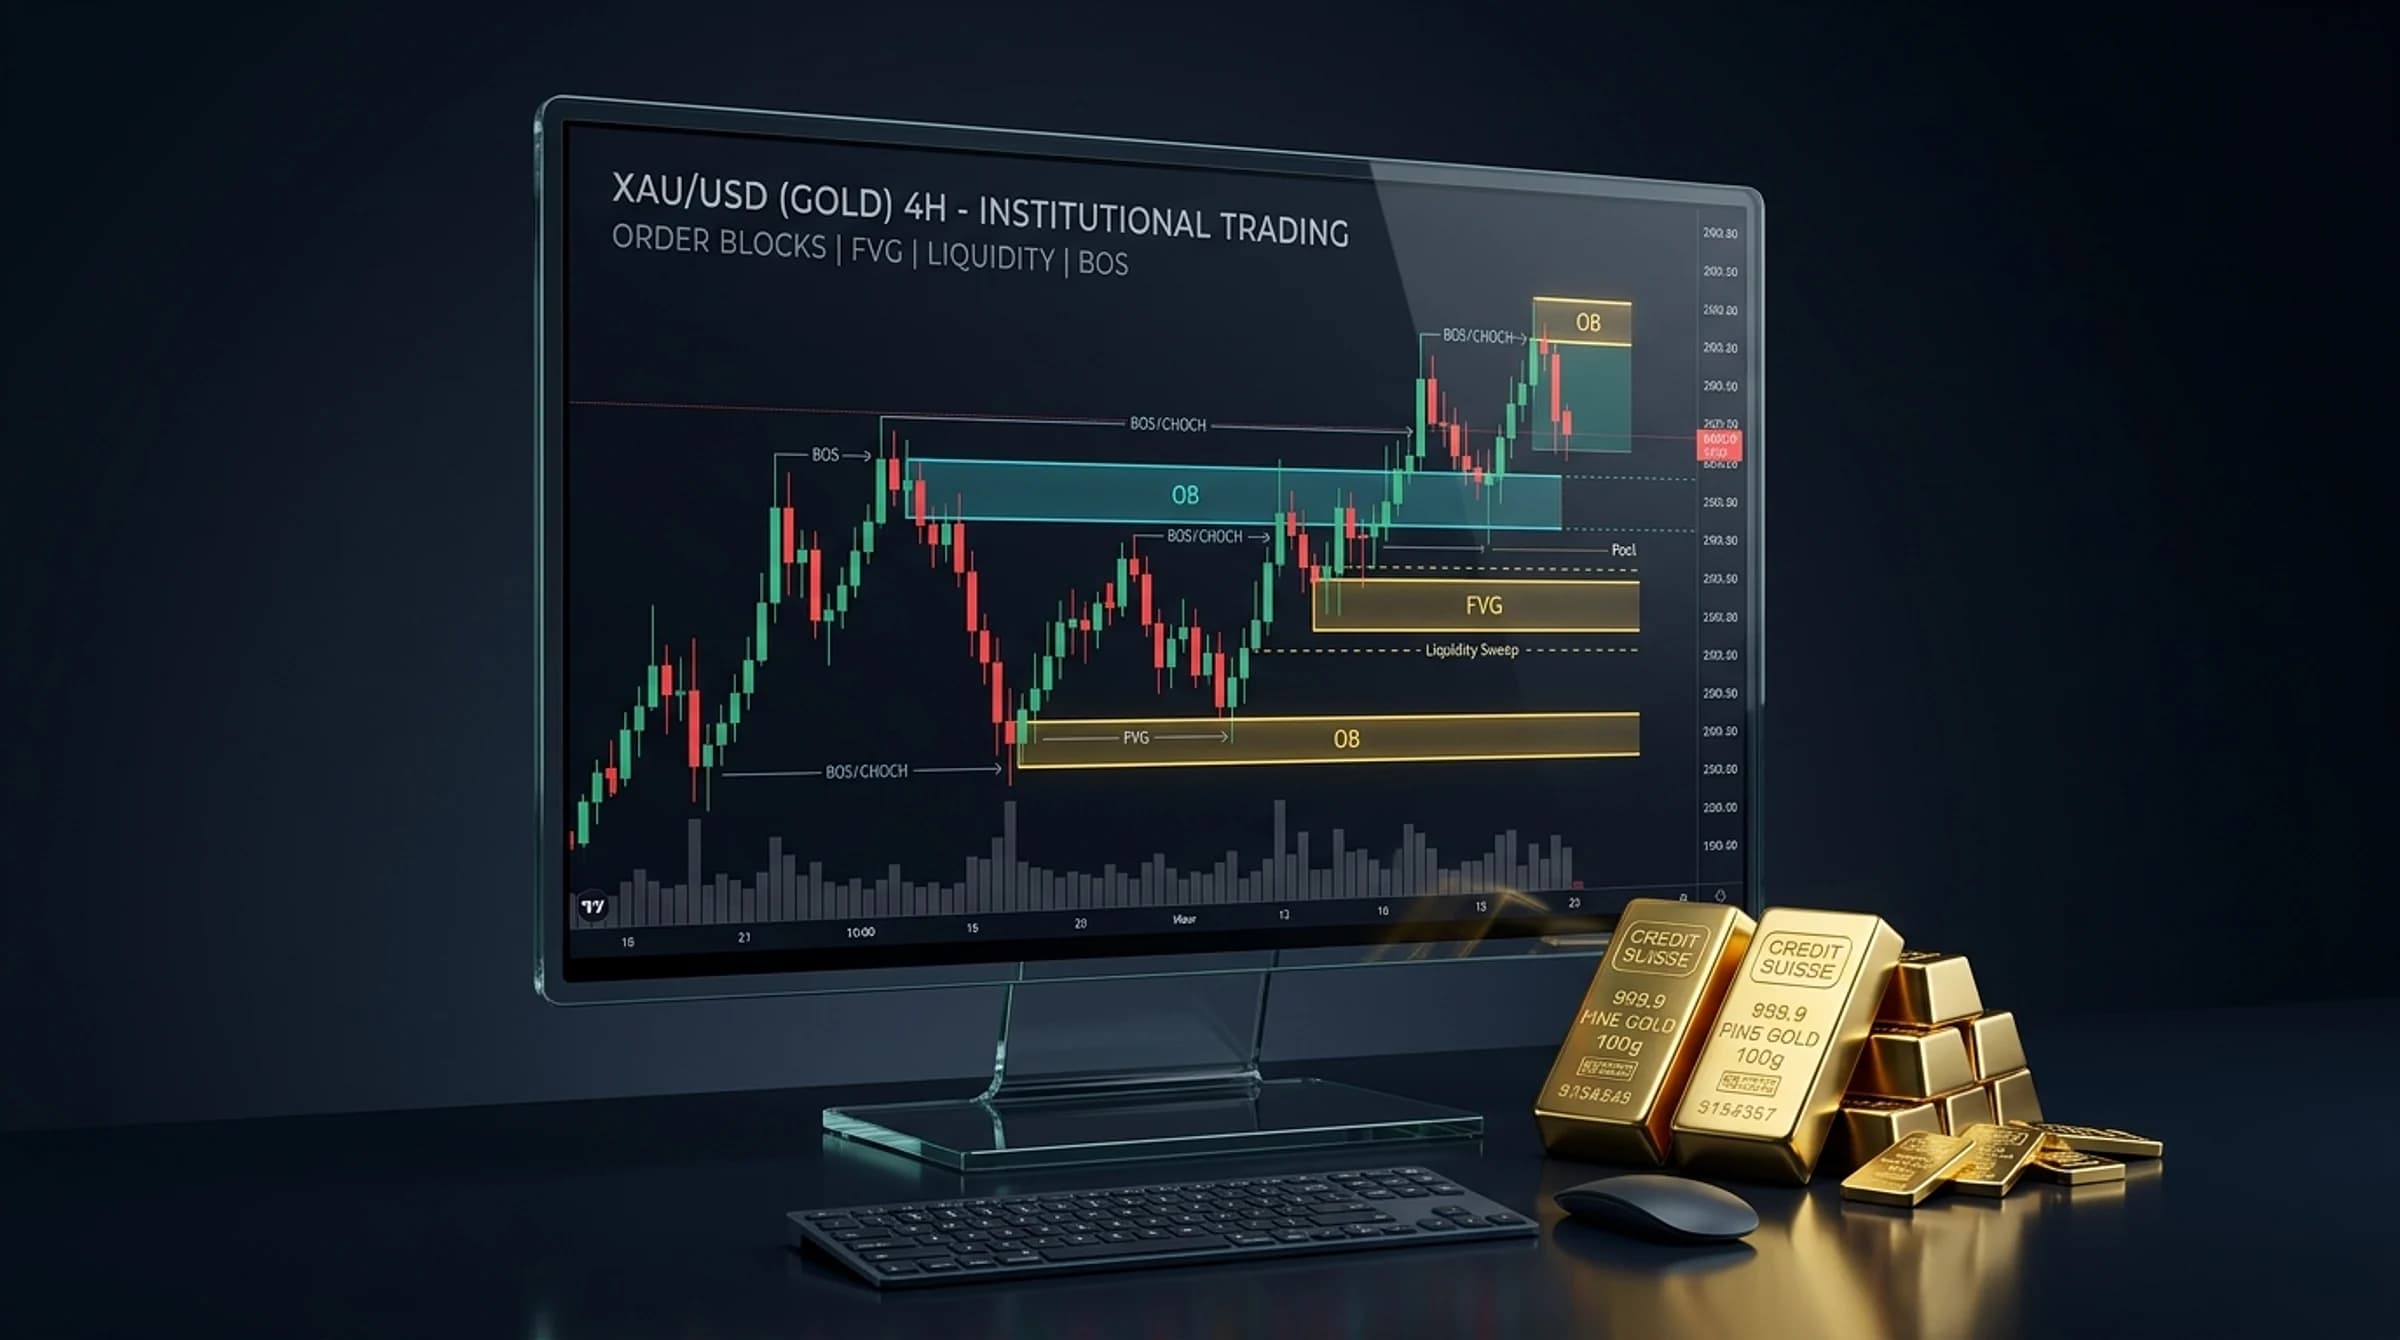
When institutional orders flood the gold market with rapid displacement, price expands too aggressively for balanced two-sided auctioning. This creates a market imbalance known as a Fair Value Gap (FVG).
An FVG is formally defined by a 3-candlestick sequence: - Bullish FVG: The space between the high of Candle 1 and the low of Candle 3, where Candle 2 is an energetic upward expansion candle. In this zone, only buy orders were executed; sellers were shut out of the auction. - Bearish FVG: The space between the low of Candle 1 and the high of Candle 3, where Candle 2 is an energetic downward expansion candle.
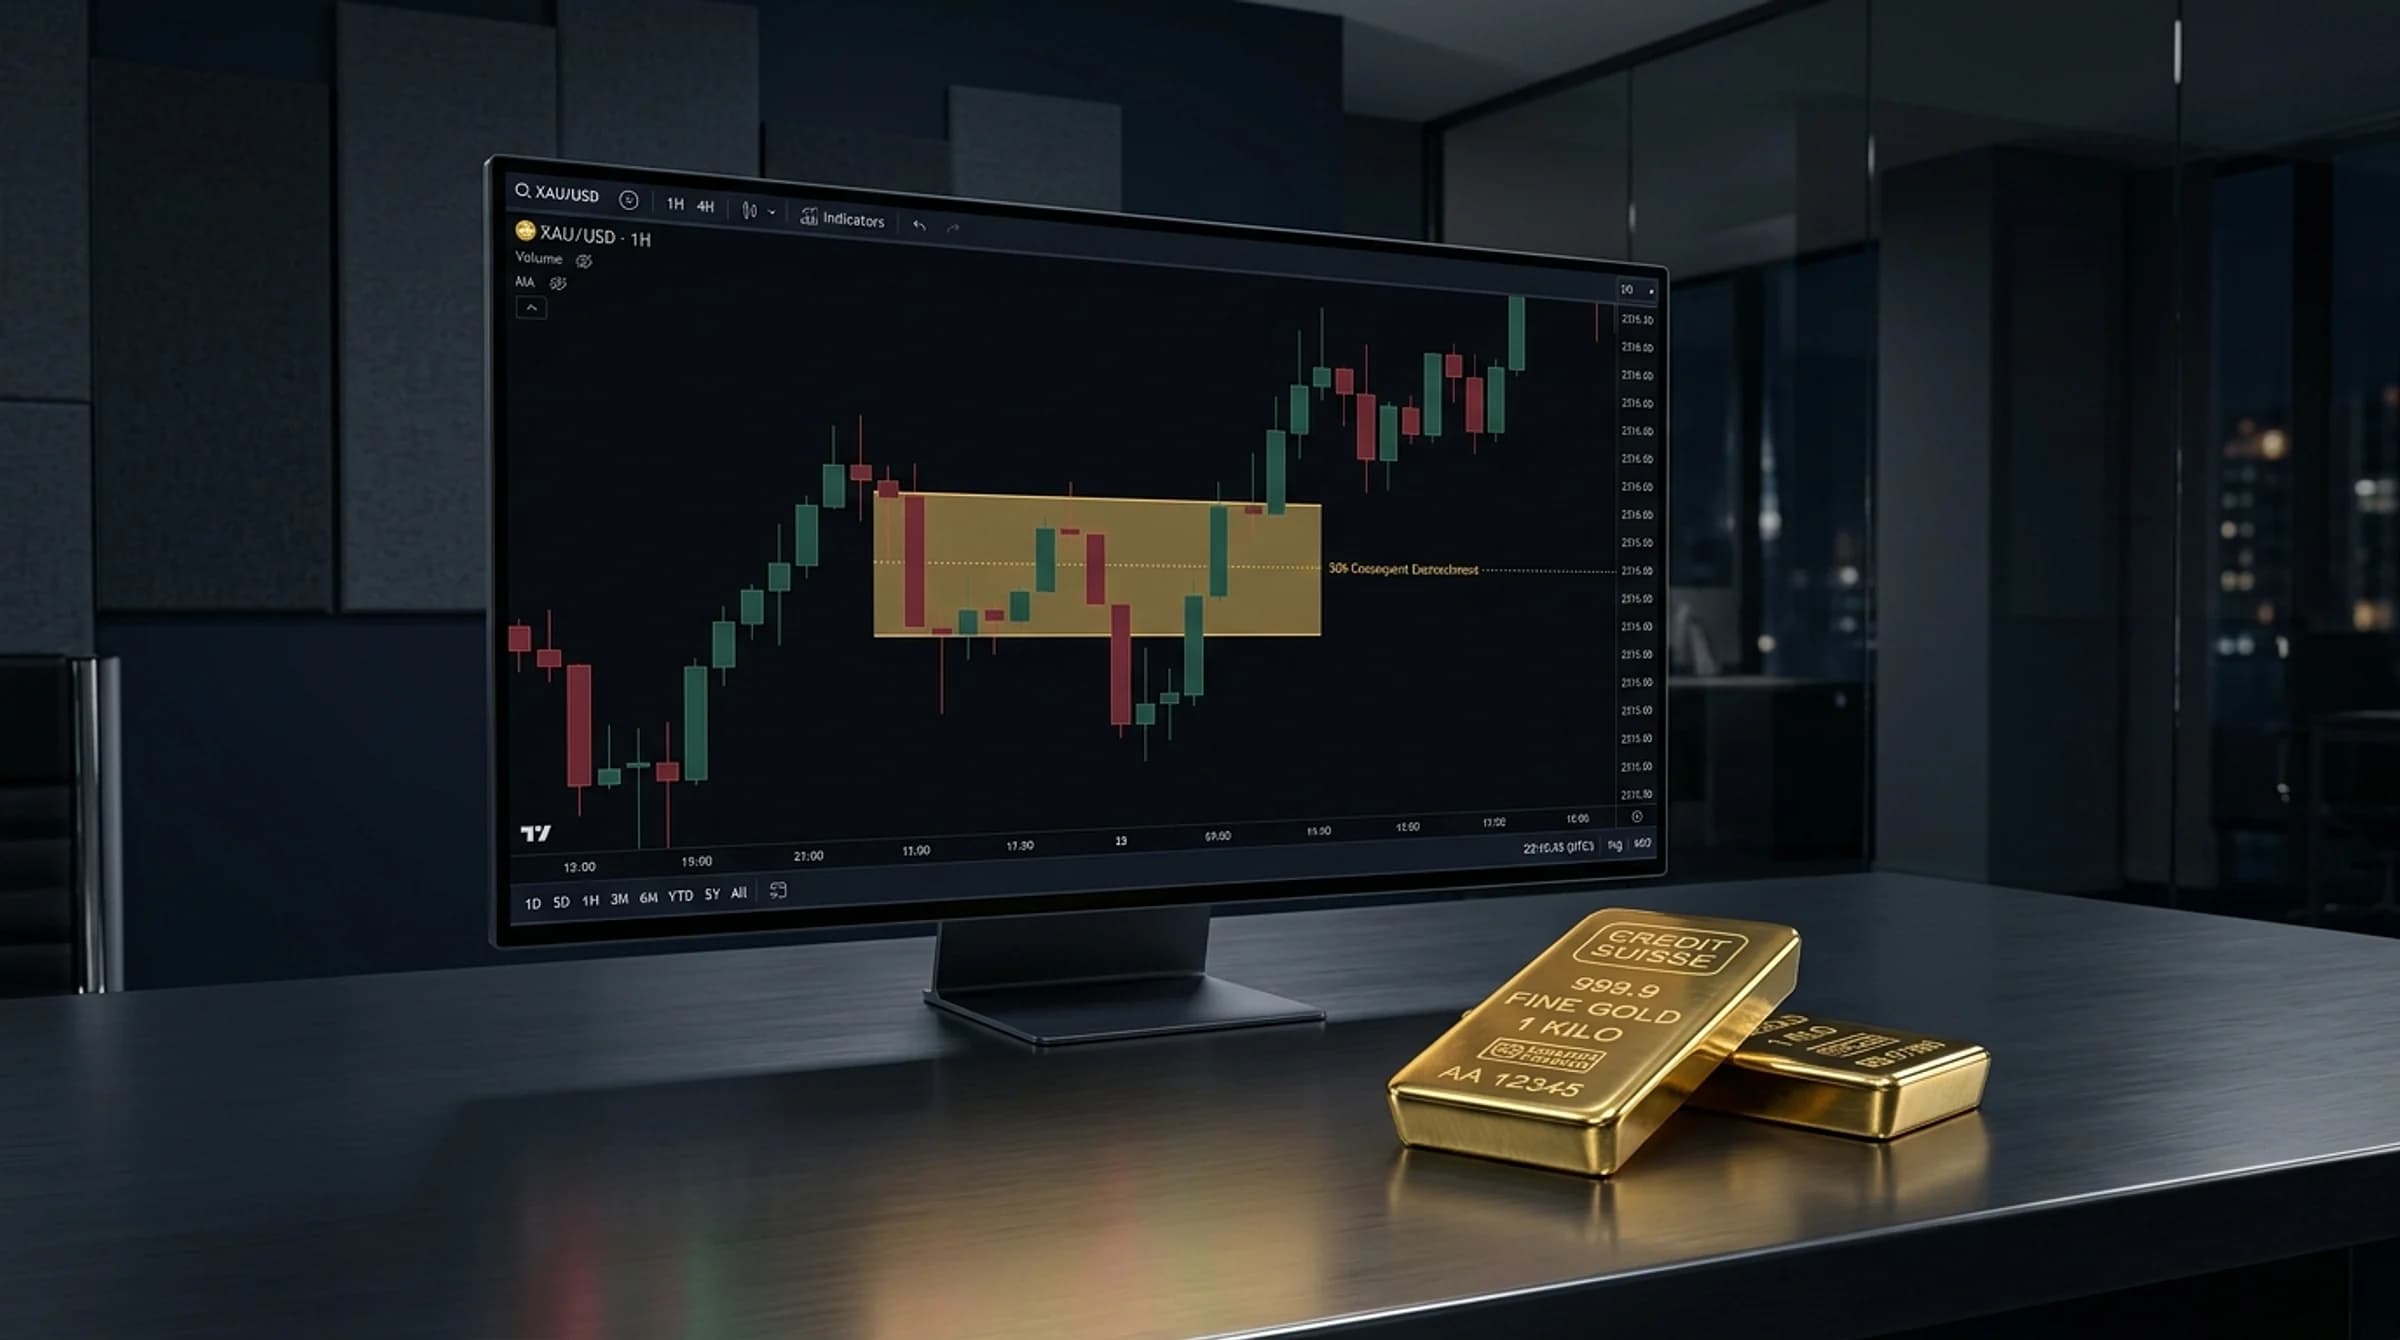
Consequent Encroachment (C.E.): The exact 50% midpoint of the Fair Value Gap is called Consequent Encroachment. Algorithms treat this level as fair market equilibrium. When price retraces back into an FVG, the 50% level provides the most statistically sensitive institutional reaction point.
If a candle wick penetrates below C.E. but the candle body closes above it, the gap remains respected. Conversely, if a full candle body closes decisively beyond Consequent Encroachment, the imbalance is considered breached, signaling setup invalidation.
Consequent Encroachment (C.E.) = Lower Boundary + [(Upper Boundary − Lower Boundary) × 0.50]4. Validating High-Probability Order Blocks & Breaker Blocks
Not every opposing candle prior to a move is an institutional Order Block (OB). Amateur SMC traders mark every candlestick on their chart, creating analysis paralysis and low win rates.
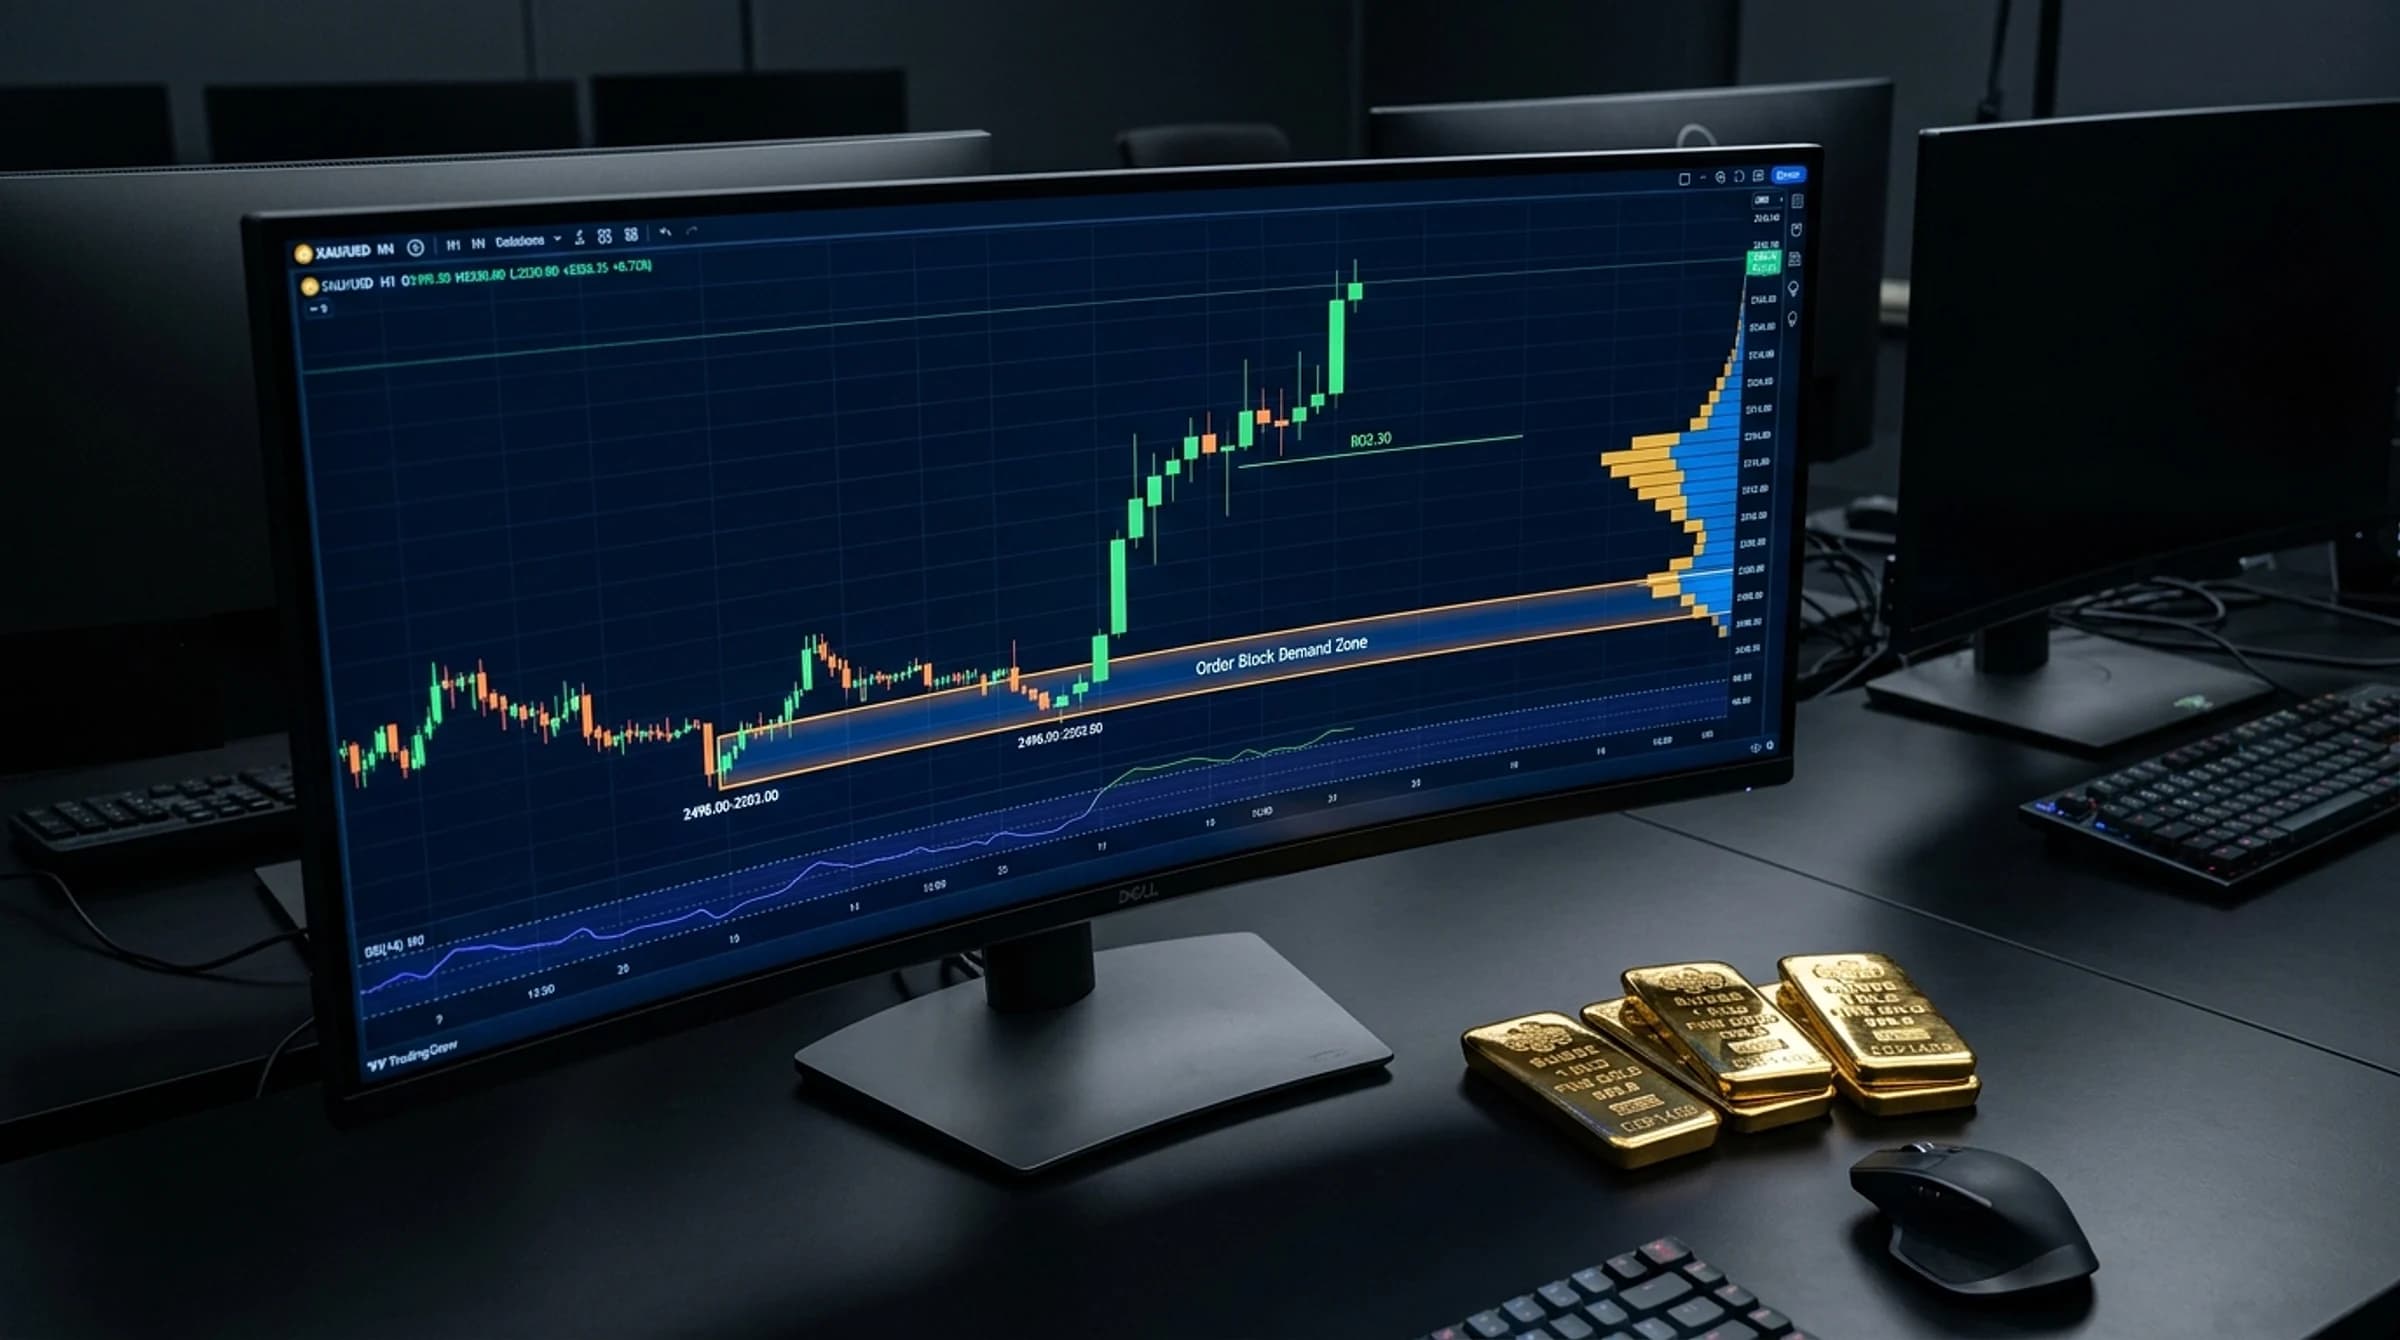
An authentic institutional Order Block must fulfill three mandatory criteria: 1. Liquidity Purge: The candle or sequence must sweep prior Buy-Side or Sell-Side Liquidity (e.g., taking out an Asian range extreme). 2. Violent Displacement: Price must reject the sweep with aggressive, one-sided movement, creating an energetic Fair Value Gap. 3. Market Structure Shift (MSS): The displacement must break a meaningful swing high (bullish OB) or swing low (bearish OB) with full candle body close.
Mean Threshold: The 50% midpoint of the Order Block body is termed the Mean Threshold. Institutional execution algorithms protect this level. Price should not close past the Mean Threshold if the order block is authentically sponsored by commercial flow.
Breaker Blocks: A Breaker Block is a failed Order Block that caused a liquidity sweep before price reversed and broke through it. In a bullish breaker, price sweeps a previous low, rallies to make a higher high, and then crashes downward through the swing low. That prior swing low order block now flips into a powerful institutional resistance ceiling.
5. Market Structure Shift (MSS) vs. Break of Structure (BOS)
Accurate trend reading requires distinguishing between trend continuation and trend reversal:
- Break of Structure (BOS): Occurs when price breaks a swing high in an established uptrend, or a swing low in an established downtrend. A BOS confirms that the prevailing institutional orderflow remains intact. - Market Structure Shift (MSS): Occurs when price breaks the key swing point that was responsible for creating the most recent extreme. In a bullish-to-bearish shift, price breaks the swing low that created the highest high.
Displacement Requirement: A genuine MSS requires energetic displacement—a wide-range candle closing decisively beyond the swing point with an associated Fair Value Gap. If price merely pokes a wick beyond the swing point and closes back inside, it is classified as a liquidity sweep or turtle soup, NOT a market structure shift.
| Concept | Candle Behavior | Trend Implication | Confirmation Signal |
|---|---|---|---|
| Break of Structure (BOS) | Candle body closes beyond trend extreme | Trend Continuation | Follow-through displacement in trend direction |
| Market Structure Shift (MSS) | Candle body closes beyond counter-swing point | Potential Trend Reversal | Must form an FVG during the break |
| Liquidity Sweep (Turtle Soup) | Wick probes beyond level, body closes inside | Imminent Counter-Rotation | Next candle engulfs or displaces opposite |
| Change of Character (CHoCH) | Lower timeframe initial break of minor swing | Early warning of pullback | Requires higher timeframe alignment |
6. The ICT Power of 3 (AMD) Daily Model for Gold
The Power of 3 (Accumulation, Manipulation, Distribution) is the cornerstone daily delivery model for XAUUSD. It describes how commercial market makers engineer liquidity across the 24-hour cycle:
1. Accumulation (Asia / 00:00–06:00 UTC): During the low-volatility Asian hours, algorithmic market makers keep gold compressed in a 10–15 dollar range. Unsuspecting retail traders place buy orders at the top and sell orders at the bottom, building dense liquidity pools above the Asian High and below the Asian Low.
2. Manipulation - The "Judas Swing" (London / 07:00–09:00 UTC): As European financial centers open, algorithms launch an aggressive directional thrust designed to deceive breakout traders. If the true institutional daily intent is bullish, London will engineer a sharp, deceptive decline that sweeps below the Asian Low, purging retail stops and triggering sell breakouts. This is the Judas Swing.
3. Distribution (London Overlap & New York / 12:00–16:00 UTC): Having absorbed sell liquidity at discount prices during the Judas Swing, smart money accumulators drive price aggressively upward, reversing through the entire daily range and distributing positions into Buy-Side Liquidity resting above the Asian High and previous day high.
7. Worked Execution Example: The London Judas Swing Long
Here is a complete, step-by-step institutional trade setup executed under the ICT London Judas Swing model:
Pre-Market Preparation (06:45 UTC): 1. Identify Asian session range: Asian High = $2,654.50 | Asian Low = $2,642.00. 2. Higher Timeframe Bias: Daily chart is bullish, holding above the 4-Hour 50% discount equilibrium. 3. Drawdown Target: Buy-Side Liquidity resting at previous day high ($2,668.00).
Execution Sequence: - 07:15 UTC (London Open): Price drops aggressively, slicing through the Asian Low ($2,642.00) down to $2,638.50. Retail breakout traders rush to short gold. - 07:25 UTC: The 5-minute chart prints an immediate rejection wick, followed by a large green displacement candle that breaks the minor swing high at $2,643.00 (MSS confirmed). - 07:30 UTC: An energetic 5-minute Fair Value Gap is left between $2,640.50 (Candle 1 high) and $2,642.50 (Candle 3 low). Consequent Encroachment (C.E.) sits at $2,641.50. - Entry: Limit order placed at $2,642.00 (top of FVG) with secondary add at C.E. ($2,641.50). Filled at 07:34 UTC. - Stop Loss: Placed safely at $2,637.50 (below the manipulation sweep wick low of $2,638.50). Risk distance = $4.50. - Take Profit 1: Asian High ($2,654.50) = $12.50 gain (1:2.77 R:R). 70% position closed. - Take Profit 2: Previous Day High ($2,668.00) = $26.00 gain (1:5.77 R:R). Remaining 30% closed. - Result: Risk strictly capped at 1% of account ($100 on $10k equity); realized profit = $362.50 USD net of commissions.
8. Invalidation & Failure Modes: When Macro Overrides SMC
The greatest hazard in trading SMC is failing to recognize when technical market structure is superseded by macroeconomic catalysts.
The Invalidation Scenario: You identify a pristine 15-minute Bullish Order Block and FVG on gold at $2,645.00 during the New York morning session. Every visual criterion matches the textbook pattern. You place a buy limit at $2,645.00 with a stop loss at $2,640.00.
The Macro Shock: At 12:30 UTC, the US Bureau of Labor Statistics releases the Consumer Price Index (CPI), coming in 0.4% above consensus expectations. US 10-Year Treasury yields surge 15 basis points in seconds.
The Failure Mechanism: 1. Macroeconomic reality dictates that institutional bullion desks must immediately reprice gold lower to reflect higher real interest rates and dollar strength. 2. The 15-minute FVG and Order Block are vaporized in a single 1-minute candle, plunging through $2,645.00, $2,640.00, and continuing straight to $2,615.00. 3. Traders who believe "order blocks always hold" get wiped out by slippage and stubborn averaging down.
Institutional Rule: Never trade SMC setups in the immediate path of Tier-1 macroeconomic data drops (CPI, NFP, FOMC). When fundamental repricing occurs, order book imbalances reflect macro orderflow, not lower-timeframe chart patterns.