1. Comparative Institutional Profiles: London vs. New York
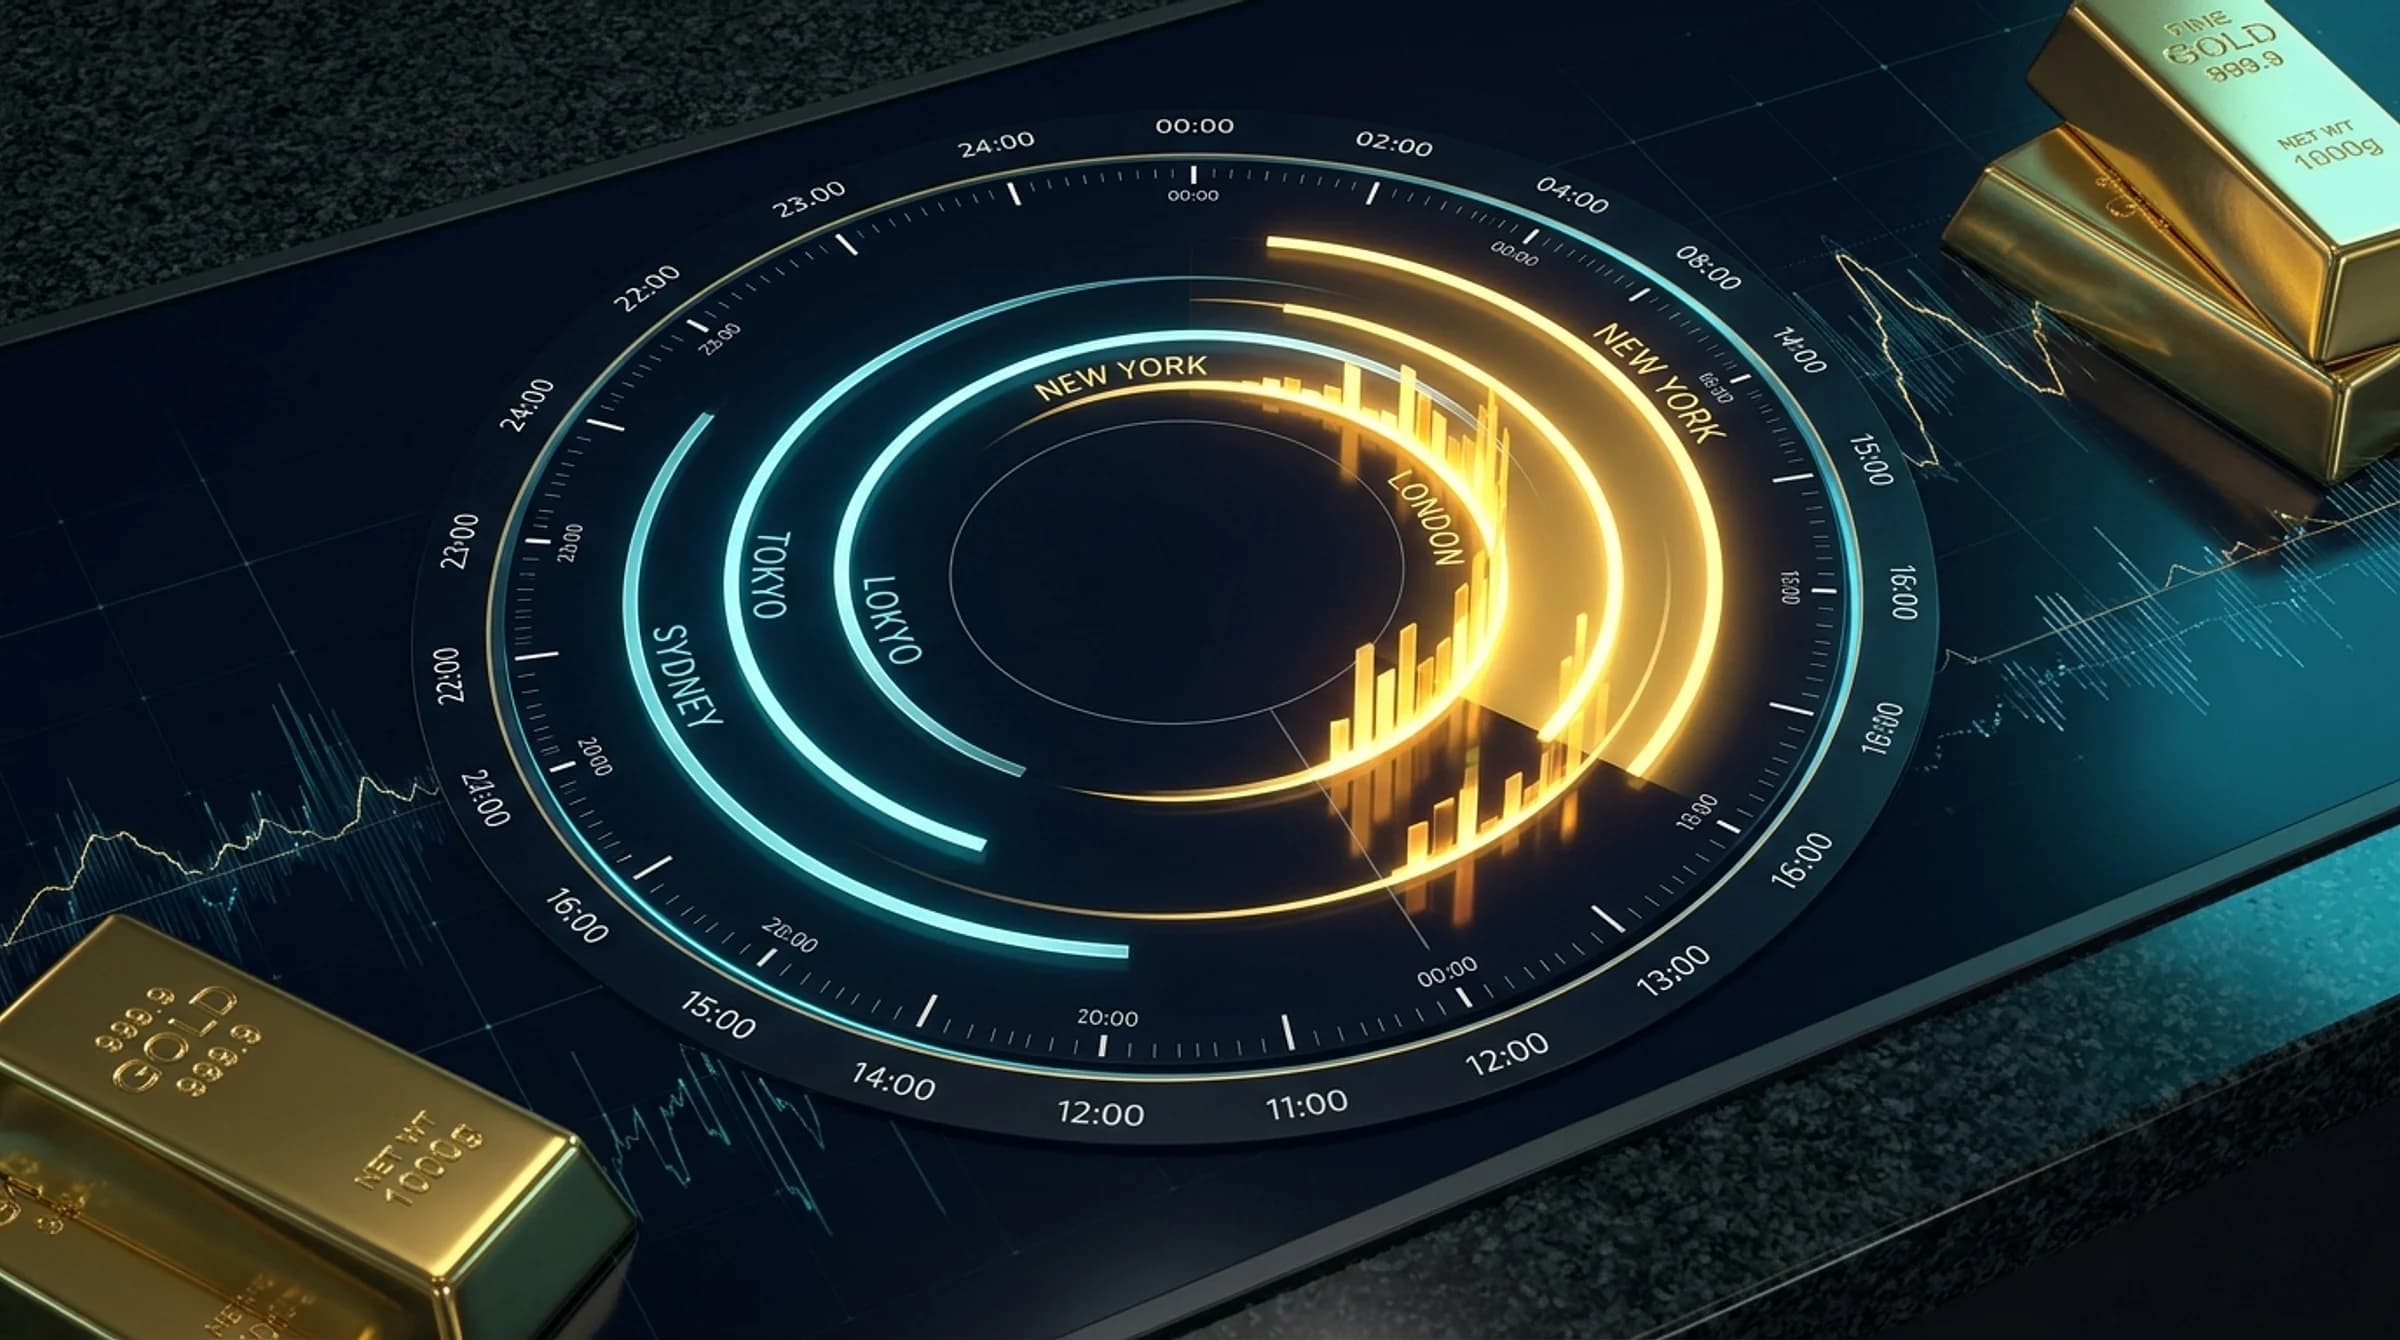
Spot gold (XAUUSD) trading is governed by two dominant financial powerhouses: London and New York. While both sessions generate substantial turnover, their institutional market participants, execution motives, and liquidity structures are fundamentally distinct:
The London Session (07:00–16:00 UTC): - Market Character: Physical Bullion Clearing & Technical Orderflow. - Primary Participants: London Bullion Market Association (LBMA) market-making banks (HSBC, JPMorgan, UBS, Standard Chartered), international refiners, central bank reserve managers, and European proprietary desks. - Execution Nature: London trades predominantly Loco London spot contracts settled through unallocated vault accounts. Price action is highly technical, with algorithms systematically testing, sweeping, and re-auctioning accumulated overnight Asian liquidity.
The New York Session (13:00–21:00 UTC): - Market Character: Speculative Derivatives & Macroeconomic Repricing. - Primary Participants: CME COMEX gold futures and options market makers, Commodity Trading Advisors (CTAs), global macro hedge funds, and North American algorithmic high-frequency trading (HFT) firms. - Execution Nature: New York is the epicenter of speculative leverage and macroeconomic news discovery. Driven by US economic releases and Federal Reserve interest-rate expectations, New York orderflow regularly unleashes explosive directional trend expansions that override morning technical patterns.
2. Hourly Tick Volume & Average Daily Range (ADR) Distribution
Quantitative analysis of intraday tick volume and price displacement reveals distinct peaks across the trading day:
| Time Window (UTC) | Session Phase | Relative Volume (%) | Avg 1-Hour Volatility ($) | Market Characteristic |
|---|---|---|---|---|
| 00:00 – 06:00 UTC | Tokyo / Asian Session | 10% – 15% | $4.00 – $8.00 | Consolidation, range-bound mean reversion |
| 07:00 – 10:00 UTC | London Open Kill Zone | 25% – 30% | $12.00 – $18.00 | High velocity; liquidity sweeps (Judas Swings) |
| 10:00 – 12:30 UTC | London Midday Lull | 10% – 15% | $6.00 – $10.00 | Orderbook balance; pre-US positioning |
| 12:30 – 16:00 UTC | London / NY Overlap | 50% – 60% | $18.00 – $32.00 | Absolute liquidity zenith; macroeconomic data drops |
| 16:00 – 19:00 UTC | New York Afternoon | 15% – 20% | $8.00 – $14.00 | Trend continuation or post-fix consolidation |
| 21:00 – 22:00 UTC | Daily Rollover / CME Halt | < 3% | $3.00 – $6.00 (Wide Spreads) | Spread expansion 5x; market settlement |
3. The LBMA Gold Price Fix: 10:30 and 15:00 UTC Auctions
A critical institutional mechanism unique to gold is the LBMA Gold Price auction, operated electronically by ICE Benchmark Administration (IBA):
- AM Fix: 10:30 UTC (05:30 EST) - PM Fix: 15:00 UTC (10:00 EST)
How the Fix Operates: The auction matches commercial buy and sell orders from direct participating bullion banks. The auction algorithm calculates whether total buy volume balances total sell volume within a 3-cent tolerance. If an imbalance exists, the price is adjusted in successive rounds until equilibrium is established.
Intraday Trading Implications: 1. Physical Balancing Flows: Sovereign wealth funds, global mining companies, and physical jewelry conglomerates submit market-on-close orders benchmarked to the 15:00 UTC fix. 2. The 14:45–15:15 UTC Volatility Surge: As participating bullion banks hedge their client fix orders in the spot and futures markets, aggressive 15-minute directional momentum surges frequently occur. Traders can identify institutional positioning by monitoring whether price sweeps or breaks structure leading into 15:00 UTC.
4. The "London Trend / New York Reversal" Paradigm
One of the most recurring statistical patterns in precious metals trading is the New York reversal of a morning London trend.
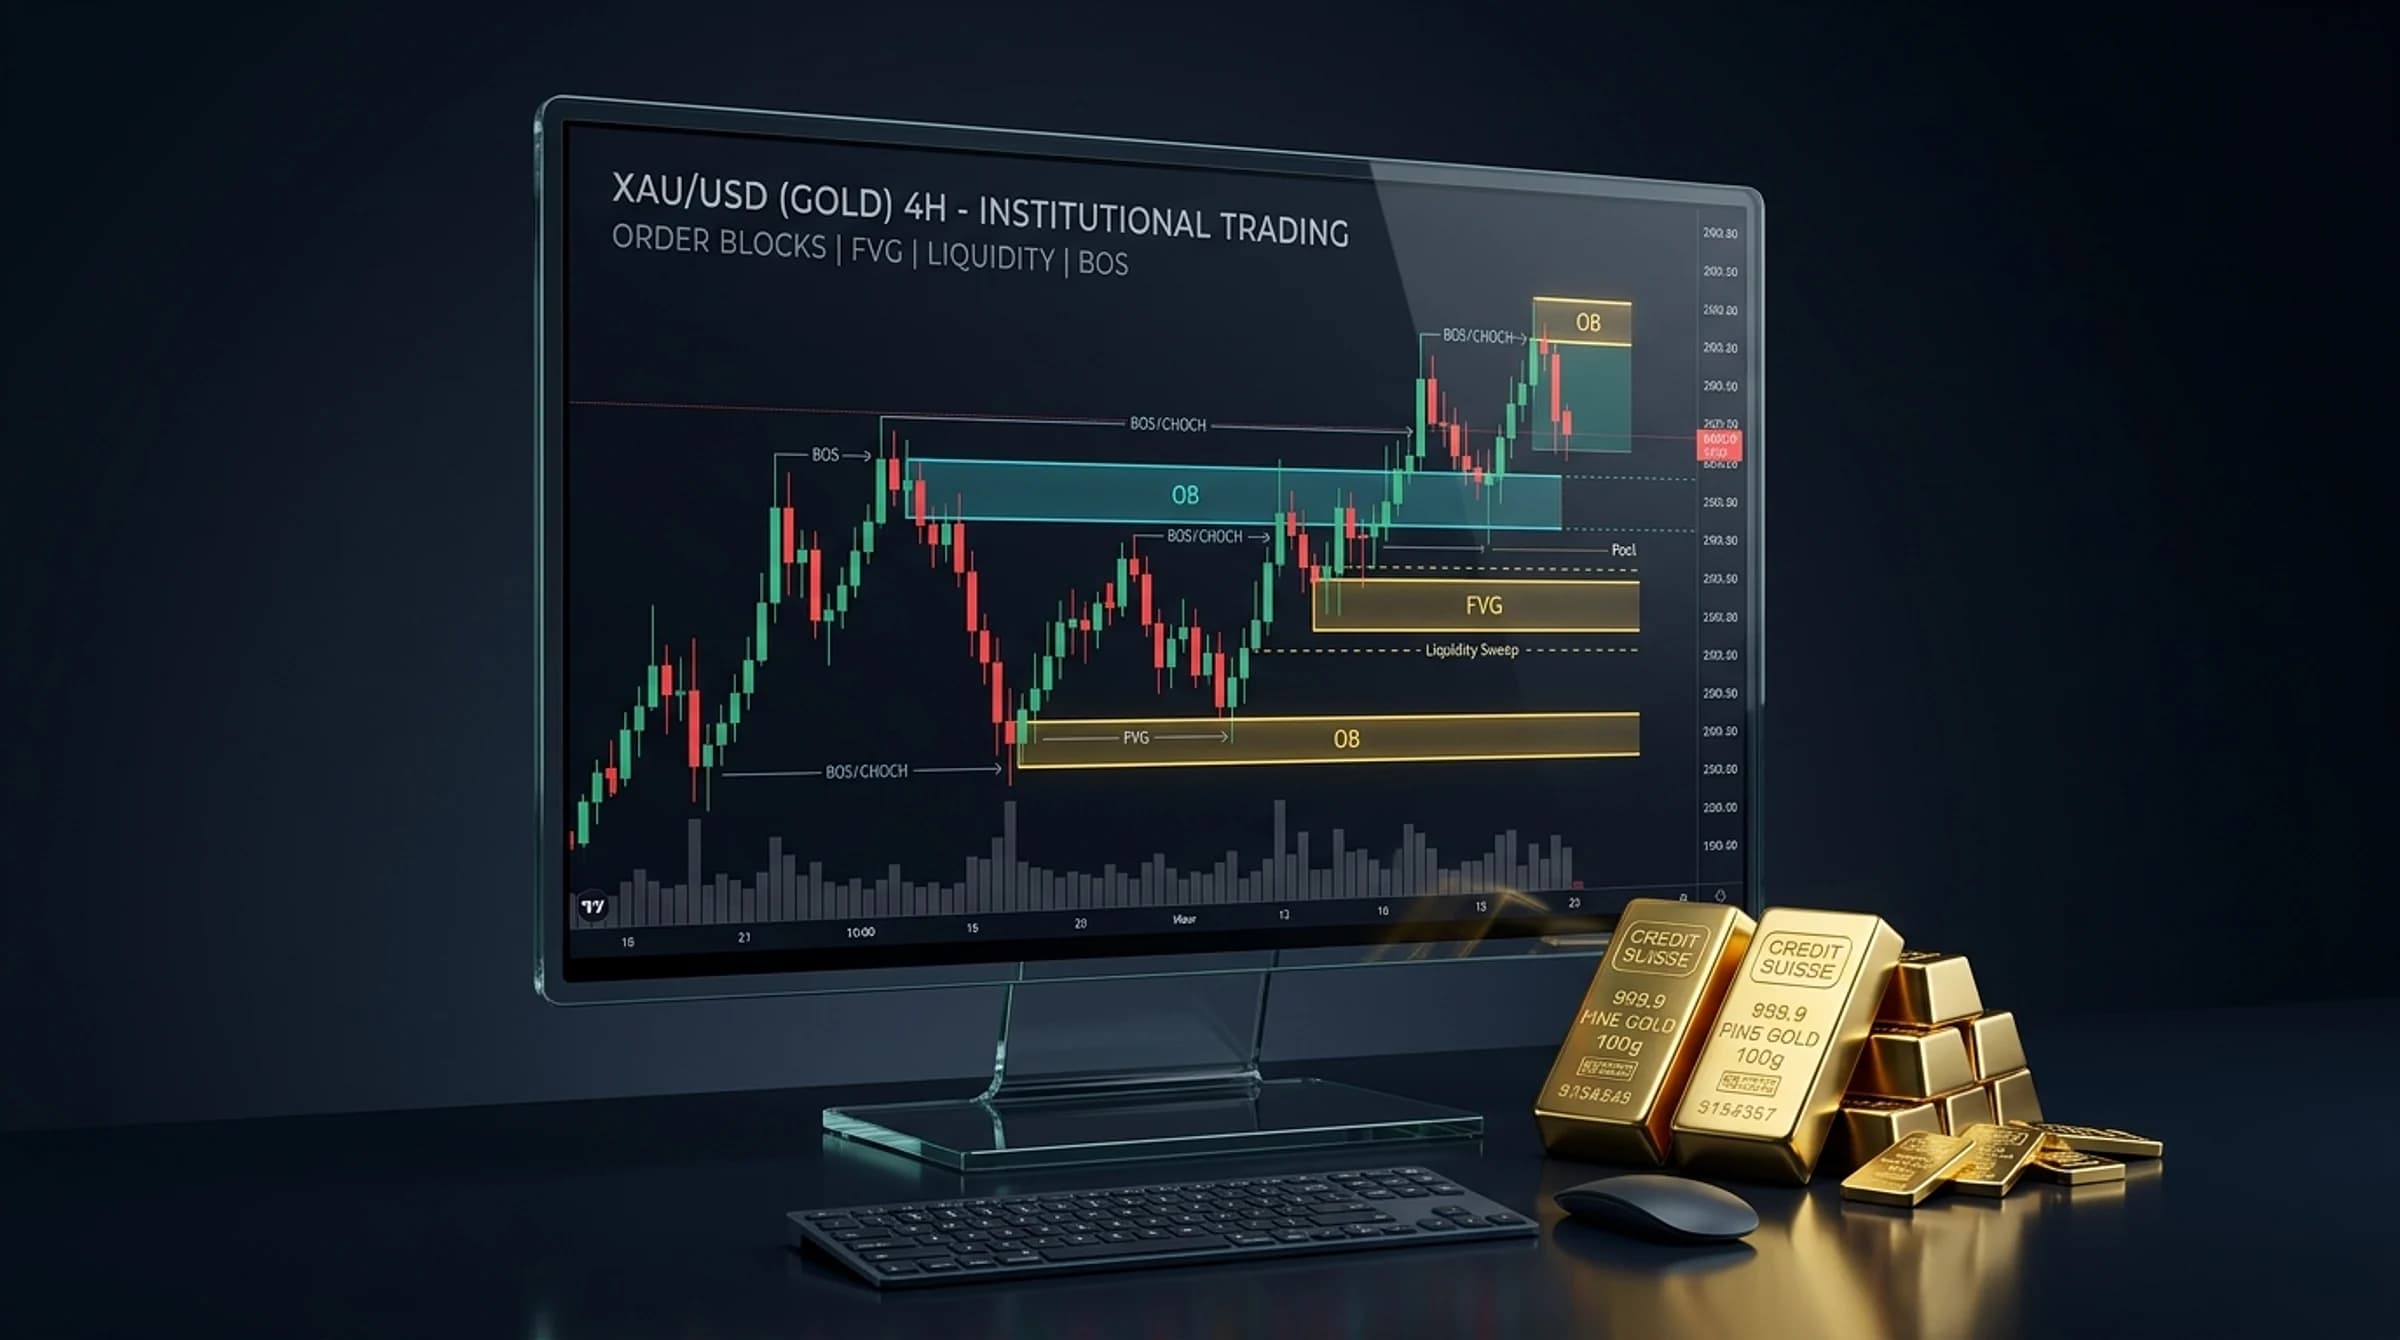
The Mechanical Anatomy of the Reversal: 1. London Establishes Morning Trend: From 07:30 to 11:30 UTC, European desks push gold steadily higher, moving price from $2,640.00 to $2,658.00. Retail traders conclude: "Gold is in a strong uptrend today." 2. The New York Catalyst (12:30 or 14:00 UTC): US economic reports (such as Core PPI, Retail Sales, or Consumer Confidence) beat consensus expectations. US bond yields spike higher. 3. The Reversal Trap: - CME futures market makers and institutional macro desks immediately sell gold to reprice higher interest-rate expectations. - The morning London trend is abruptly halted at $2,660.00, forming a bearish Market Structure Shift on the 15-minute chart. - Gold reverses violently, plunging through the entire morning London range and breaking below $2,635.00 by 15:30 UTC.
Strategic Rule: Never assume that a morning London trend will automatically continue throughout the New York afternoon. Always re-evaluate market structure when New York opens and verify whether upcoming US macroeconomic data aligns with the prevailing trend.
5. Broker Spread Dynamics & Slippage Across Sessions
Execution quality varies significantly between the two major sessions:
- Raw ECN Spreads: During the London/New York overlap (13:00–16:00 UTC), intense competition among tier-1 liquidity providers compresses raw ECN spreads to 8 to 15 points ($0.08–$0.15/oz). In early London (07:00–08:00 UTC), spreads average 15 to 25 points ($0.15–$0.25/oz). - Slippage Profile: Slippage during normal London open conditions is generally mild (1–5 points). However, during New York data drops (CPI or NFP at 12:30/13:30 UTC), market orders regularly experience 10 to 40 points of negative slippage ($0.10–$0.40/oz) as order book depth evaporates. - Stop-Order Integrity: Resting limit orders are filled with high reliability during the London/NY overlap due to deep continuous market making.
6. Worked Comparative Trade Scenario: Navigating the Session Transition
Here is a real-world case study illustrating how an institutional trader manages a position across the London-to-New York handover:
Morning London Trade (08:00 UTC): - Setup: London sweeps Asian low ($2,642.00) down to $2,638.00, prints 5M MSS, and fills a long entry at $2,641.50 with stop loss at $2,636.50 ($5.00 risk). - Target: Previous day high at $2,658.00 ($16.50 gain). - Progression: By 11:30 UTC, gold rallies smoothly to $2,656.00 (+ $14.50).
The New York Handover Management (12:15 UTC): - Calendar Check: US Initial Jobless Claims and Philly Fed Manufacturing Index due at 12:30 UTC. - Risk Decision: The trader recognizes the "London Trend / NY Trap" risk. Instead of holding the full position through the news release, the trader scales out 80% of volume at $2,656.00, locking in a 1:2.9 R:R profit ($232.00 on $80 risk). - Stop Adjustment: The remaining 20% runner's stop loss is moved to breakeven ($2,641.50).
Post-News Reaction (12:30 UTC): - Philly Fed index prints significantly stronger than expected. US 10-Year Treasury yields surge. - Gold immediately prints a 5-minute red candle that plunges $18.00 from $2,656.00 to $2,638.00. - Outcome: The 20% runner stops out at breakeven ($0 loss), while the 80% scaled position captured peak London gains. By recognizing session transition mechanics, the trader preserved full profitability.
7. The Trader's Session Selection Framework
Which session should you trade? Your choice should align with your psychological profile, timezone, and strategy:
| Criteria | London Session (07:00–10:00 UTC) | New York Session (13:00–16:00 UTC) | Optimal Trading Style |
|---|---|---|---|
| Best Strategy | ICT Judas Swing & Liquidity Sweep reversals | Macro trend continuation & FVG pullbacks | Discretionary price action |
| Volatility Pace | Orderly, technical, smooth expansions | High velocity, aggressive repricing | Patience in London; fast reflexes in NY |
| News Risk | Low (occasional European/UK CPI/PMI) | Very High (Tier-1 US data drops daily) | Lock execution during US news |
| Execution Spreads | Tight ($0.15–$0.25) | Tightest ($0.08–$0.15) | Raw ECN accounts recommended |
| Recommended For | Technical purists & patient swing day traders | Momentum scalpers & macro-aware traders | Select session matching your local timezone |