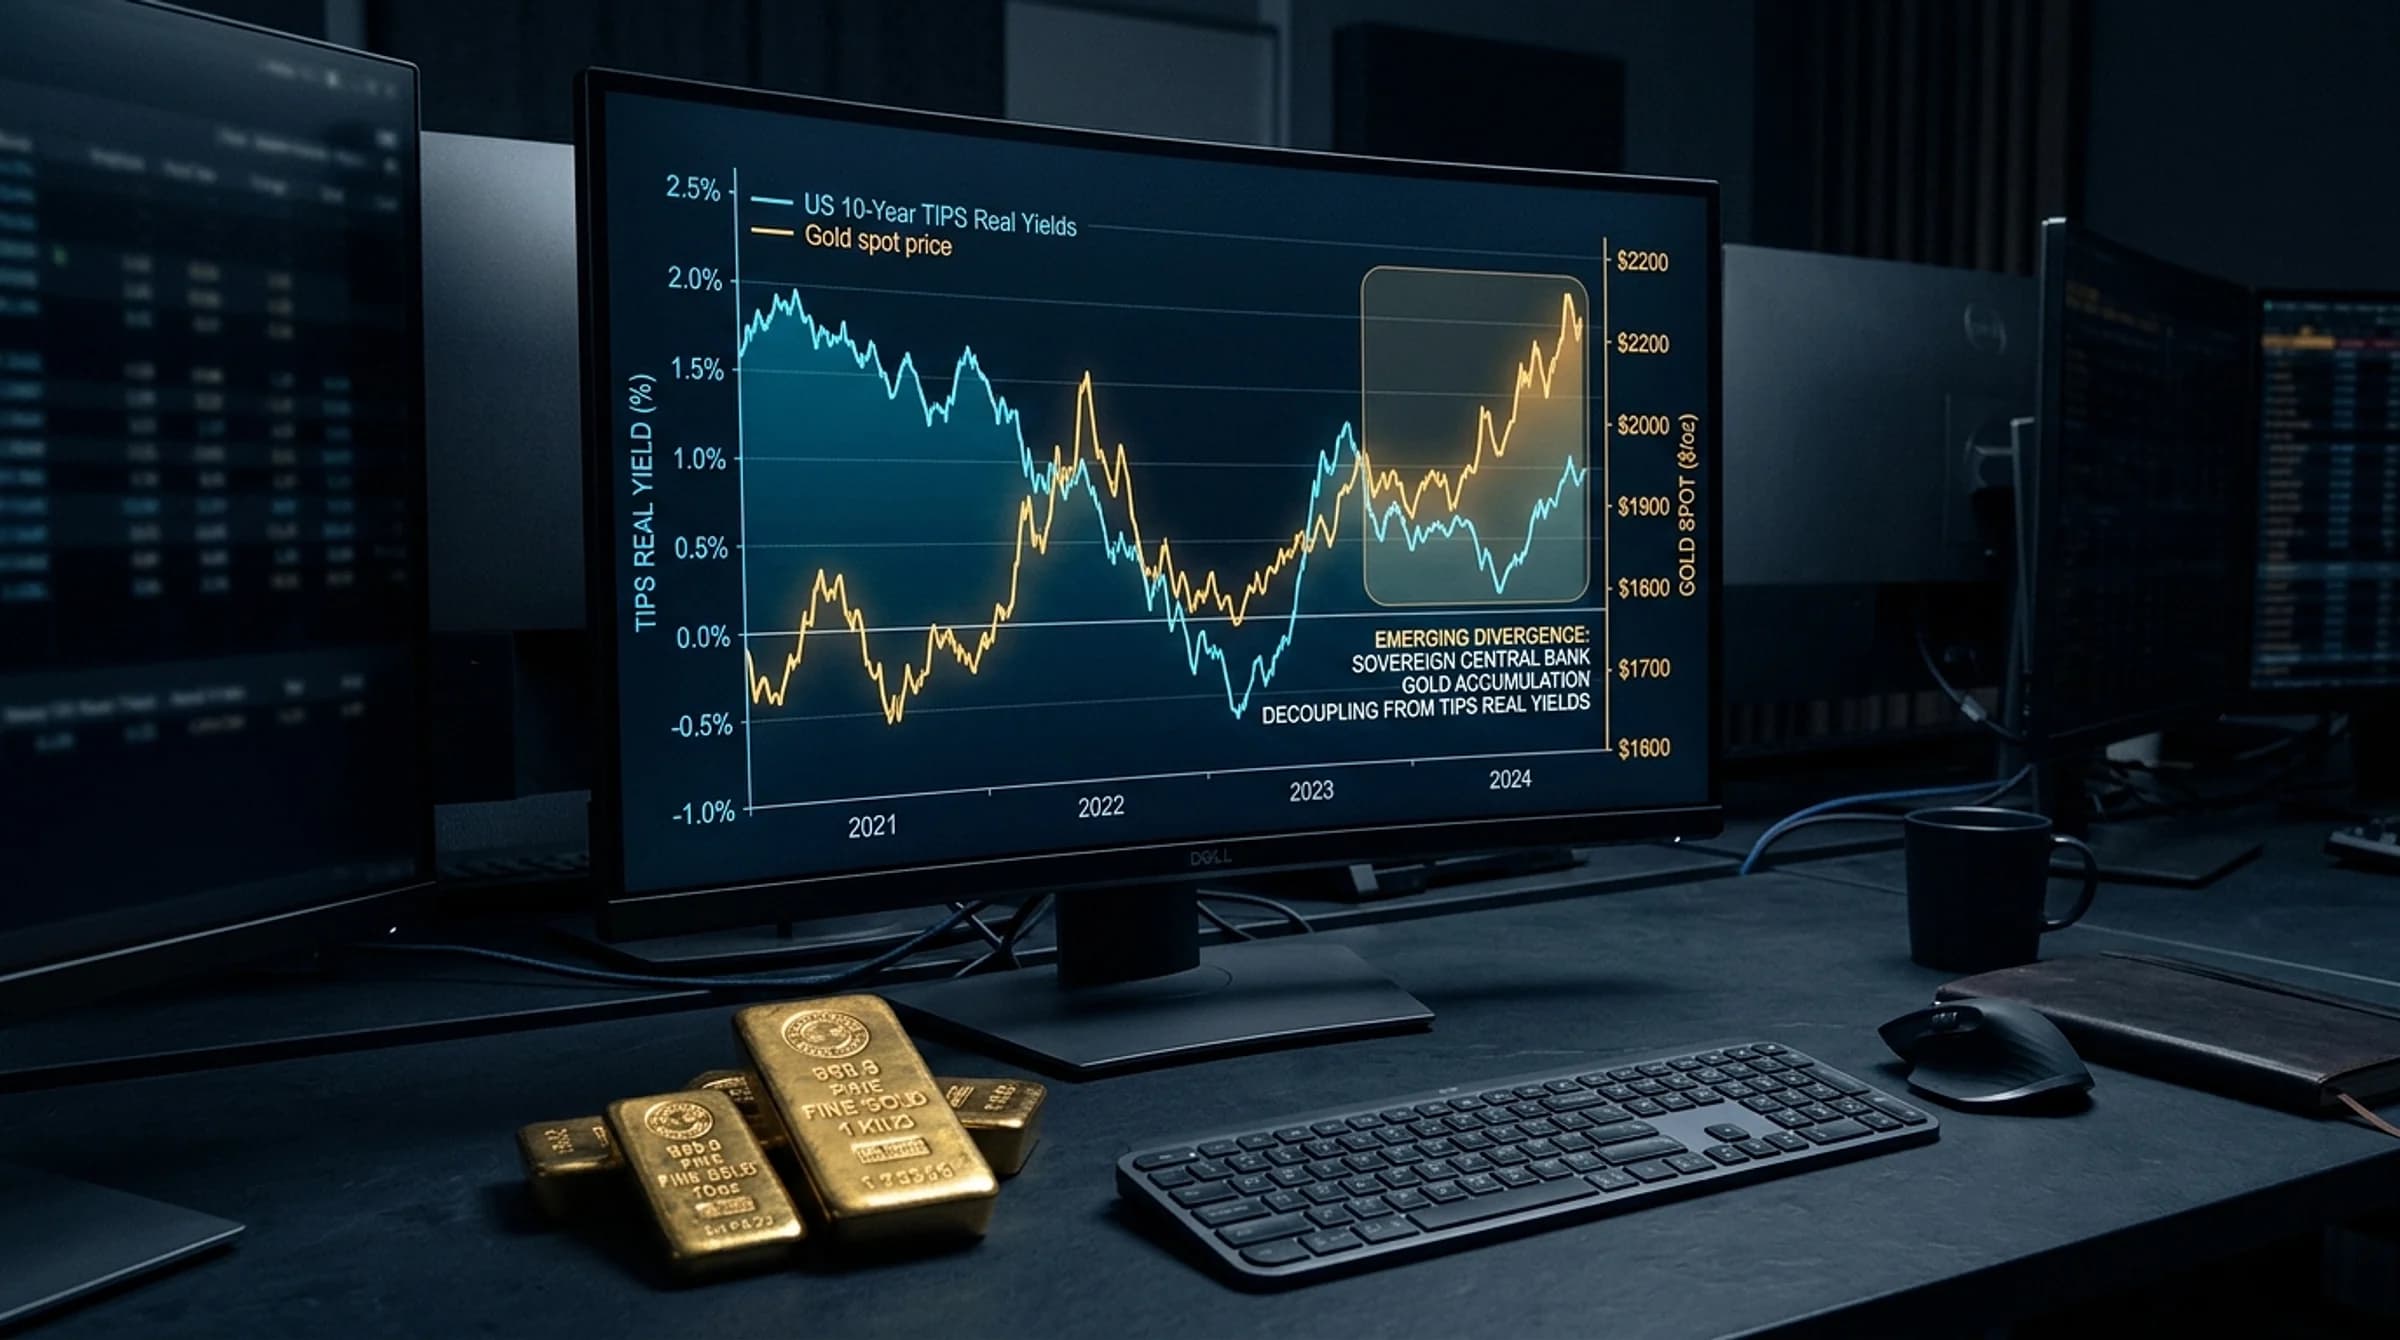
1. The 10-Year TIPS Valuation Anchor: Opportunity Cost Mechanics
In modern institutional asset management, gold is classified as a zero-coupon, perpetual monetary asset. Unlike sovereign debt (Treasuries), corporate bonds, or dividend-paying equities, gold yields no interest.
Consequently, an institutional investor allocating capital into physical bullion forgives the risk-free yield available on alternative sovereign instruments. This forgone return is the opportunity cost of holding gold.
The Fisher Equation Decomposition: Nominal 10-Year Treasury Yield = 10-Year Real Yield + 10-Year Expected Inflation (Breakeven Rate) Real Yield = Nominal 10-Year Treasury Yield − 10-Year Breakeven Inflation Rate
Why TIPS Represent the Purest Fundamental Benchmark: Treasury Inflation-Protected Securities (TIPS) are sovereign bonds whose principal value adjusts automatically with the Consumer Price Index (CPI). Therefore, the quoted yield on a 10-Year TIPS note (tracked officially by the Federal Reserve Bank of St. Louis under series DFII10) is an exact market-derived measure of the real purchasing power return guaranteed by the US government.
When real risk-free yields are high (e.g., +2.00% to +2.50%), holding risk-free Treasury paper provides attractive real capital growth. Institutional pension funds and endowments are economically pressured to rotate out of non-yielding precious metals into sovereign bonds.
Conversely, when real yields plunge toward zero or become negative (meaning nominal bond yields lag behind inflation), holding paper debt guarantees real wealth destruction. Under negative real yield regimes, the opportunity cost of holding physical bullion collapses to zero, driving massive institutional capital into precious metals.
Real Yield (DFII10) = Nominal 10Y Treasury Yield − 10Y Breakeven Inflation Rate2. Econometric Regression History & Scatter Plot Metrics (2003–2021)
Between the inception of the TIPS market in 2003 and the structural shocks of 2021, the econometric relationship between the 10-Year TIPS real yield (DFII10) and spot gold (XAUUSD) was among the most robust in global macro finance:
- Regression R² (Coefficient of Determination): Averaged 0.72 over an 18-year sample period. Over 70% of the variance in gold prices was statistically explained by changes in 10-Year US Real Yields alone. - Correlation Coefficient (r): Sustained an average of −0.82. - Elasticity Beta: Statistical regression established that every 100 basis point (1.0%) decline in 10-Year real yields generated an approximate $140 to $180 per ounce appreciation in spot gold.
During this era, institutional macro desks operated a straightforward playbook: track the daily Treasury auction results and FRED DFII10 series. If real yields were declining, gold was an aggressive overweight allocation.
| Historical Era | 10Y TIPS Yield Range | Gold Price Range | Observed Inverse Relationship | Primary Macro Catalyst |
|---|---|---|---|---|
| 2004–2007 | +1.60% to +2.60% | $400 – $800 / oz | Consistent inverse tracking | Global economic expansion; moderate real rates |
| 2008–2012 | +1.80% down to −0.85% | $700 – $1,920 / oz | Parabolic gold surge as real rates turned negative | Federal Reserve QE1, QE2, and ZIRP policy |
| 2013–2018 | −0.85% up to +1.15% | $1,900 down to $1,180 / oz | Prolonged gold bear market as real rates recovered | Fed taper tantrum and balance sheet normalization |
| 2019–2021 | +0.60% down to −1.10% | $1,270 up to $2,075 / oz | Massive bull run into record all-time highs | COVID-19 pandemic emergency stimulus |
3. The Post-2022 Regime Shift: Econometric Analysis of the Decoupling
In 2022, traditional econometric gold models failed catastrophically. In response to 40-year-high inflation, the Federal Reserve initiated its most aggressive interest rate hiking cycle in four decades, raising the benchmark Fed Funds Rate by 525 basis points.
US 10-Year TIPS real yields rocketed from −1.10% in November 2021 to over +2.50% in October 2023—a monumental 360 basis point tightening in real sovereign borrowing costs.
Under legacy econometric models, this historic surge in real yields should have triggered a devastating collapse in gold, driving prices down toward $1,100–$1,300 per ounce. Western investment institutions obeyed the legacy models: SPDR Gold Shares (GLD) and European physical gold ETFs experienced massive cumulative outflows of over 800 metric tons.
Yet spot gold defied the model entirely: - Gold formed a firm floor at $1,615–$1,620 in late 2022. - In 2023 and 2024, while real yields remained elevated above +2.00%, gold staged an explosive breakout, surging past $2,000, $2,400, and $2,700 to new all-time highs. - The 20-year rolling correlation between 10-Year TIPS and gold flipped from −0.82 to POSITIVE (+0.42).
What caused this structural decoupling? 1. Sanctions on Foreign Exchange Reserves: The freezing of $300 billion in Russian G7-held reserves fundamentally altered sovereign risk perception. Sovereign central banks recognized that Western government bonds carry legal confiscation risk, while physical gold stored in sovereign vaults carries zero counterparty or sanctions risk. 2. Inelastic Sovereign Demand: Non-Western central banks (PBoC, RBI, CBR, NBP) purchased record volumes of physical bullion (> 1,000 metric tons/year) with complete price-inelasticity. Sovereign buying absorbed all Western ETF liquidation volume and overwhelmed the mathematical drag of high real interest rates. 3. Fiscal Dominance Concerns: Growing global institutional recognition that US national debt ($35+ trillion) cannot be repaid without eventual currency debasement or artificial financial repression.
4. How Institutional Desks Track FRED: DFII10 in Real Time
To incorporate real yields into your trading routine, follow the institutional monitoring protocol:
Official Benchmark: - FRED Series: DFII10 (Market Yield on U.S. Treasury Securities at 10-Year Constant Maturity, Quoted on an Investment Basis, Inflation-Indexed). - Release Frequency: Daily at approximately 16:00 ET (21:00 UTC) by the US Department of the Treasury.
Real-Time Intraday Proxies: Because the official DFII10 series updates only once daily after market close, intraday traders utilize real-time market proxies: 1. iShares TIPS Bond ETF (Ticker: TIP): Invert the TIP chart. When TIP rises, real yields are falling (bullish for gold). When TIP falls, real yields are rising (bearish for gold). 2. The Synthetic 10Y Spread: Monitor the nominal 10-Year Treasury Yield (US10Y) minus the 10-Year Breakeven Inflation Rate (T10YIE). If nominal Treasury yields are falling faster than inflation expectations, real yields are compressing—providing immediate intraday bullish momentum for XAUUSD.
5. Worked Practical Analysis: Integrating Real Yields into Daily Bias
Here is a real-world workflow showing how an institutional gold analyst uses real yield telemetry to filter intraday trade setups:
Pre-Market Data Review (06:30 UTC): 1. Nominal 10-Year Treasury Yield (US10Y): Dropped from 4.35% to 4.20% (-15 bps) overnight following dovish Federal Reserve commentary. 2. 10-Year Breakeven Inflation (T10YIE): Remained static at 2.30%. 3. Real Yield Calculation: 4.20% − 2.30% = 1.90% (declined from 2.05%, down 15 bps). 4. Sovereign Flow Check: Shanghai Gold Exchange physical premium is robust at +$28.00/oz.
Strategic Conclusion: Real yields are experiencing strong intraday downward compression. The opportunity cost of holding gold is shrinking. - Directive: Issue a strong Bullish Intraday Bias. - Tactical Filter: Filter out all 15-minute and 5-minute bearish signals. Execute only Long setups (London Judas Swings sweeping Asian lows, discount Fair Value Gap pullbacks). - Result: Gold surges $28.00 during the London and New York overlap, perfectly validating the fundamental tailwind established by declining real yields.
6. The Future of Real Yield Modeling: Limitations and Adaptation
Quantitative analysts must adapt legacy models to modern multi-polar financial realities:
1. Real Yields Are a "Speed Brake," Not a Wall: In the post-2022 regime, rising real yields no longer prevent gold bull markets; instead, they act as temporary headwinds that slow the pace of expansion. When real yields surge, gold consolidates; when real yields decline even slightly, gold surges aggressively.
2. Watch the TIPS Curve Inversion: Inversions between 5-Year TIPS (DFII5) and 10-Year TIPS (DFII10) signal acute short-term monetary policy stress, frequently preceding major sovereign monetary pivots.
3. The Sovereign Floor: As long as global central banks face geopolitical fragmentation and de-dollarization pressures, sovereign physical accumulation will provide a structural put option beneath the gold market, rendering deep cyclical bear markets unlikely even in high-real-yield environments.